
Structural Insulated Panels Market Size (By Product Type, By Sheathing Type, By Application, By End-User, and By Geography) - Global Industry, Share, Analysis, Trends and Forecast 2025 - 2033
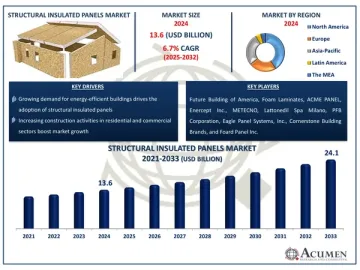
The Global Structural Insulated Panels Market Size accounted for USD 13.6 Billion in 2024 and is estimated to achieve a market size of USD 24.1 Billion by 2033 growing at a CAGR of 6.7% from 2025 to 2033.
- Last Updated: 17 Dec 2019
- Report Code: ARC1647
- Category: Construction and Manufacturing
The Global Structural Insulated Panels Market Size accounted for USD 13.6 Billion in 2024 and is estimated to achieve a market size of USD 24.1 Billion by 2033 growing at a CAGR of 6.7% from 2025 to 2033.
Structural Insulated Panels Market Highlights
- The global structural insulated panels market is expected to reach USD 24.1 billion by 2033, with a CAGR of 6.7% from 2025 to 2033
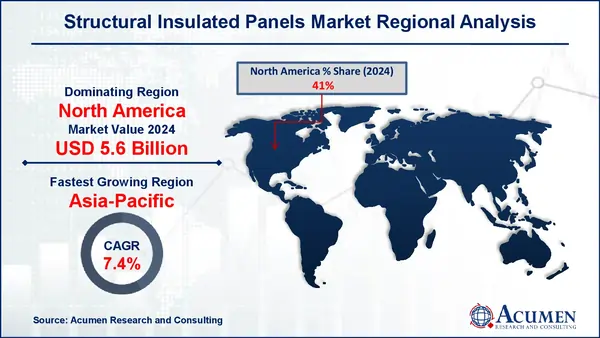
- The North America structural insulated panels market was valued at approximately USD 5.6 billion in 2024
- The Asia-Pacific market is projected to grow at a CAGR of over 7.4% from 2025 to 2033
- The polystyrene product type sub-segment accounted noteworthy structural insulated panels market share in 2024
- Within application category the walls sub-segment generate around USD 7.9 billion revenue in the market
- Innovations in eco-friendly SIP materials improve market adoption and environmental benefits is a popular structural insulated panels market trend that fuels the industry demand
The requirement for strong-performance and green building systems with eco-friendly materials is expected to further boost consumer demand on the market. Structural panels are prefabricated construction materials that facilitate and speed up the process of installation without affecting the quality of construction. In addition, cold-storage systems are projected to grow in the food and drink sector to have a positive impact on market growth. During the forecast period, residential and commercial pipeline projects would probably support consumer demand. The demand for structural insulated panels is also anticipated to grow in isolating patterns for energy efficient and sustainable building. Hence, uplifting the demand for SIP over the coming years. Structural-insulated panels are very heat and cold tolerant and therefore help to maintain an optimum level of the space climate, leading to low electricity costs. But the biggest obstacle for the industry is projected to be high commodity prices and transport costs for rigid insulated boards. The review of the SIP application assessment and its disadvantages clearly indicate the need for further studies to be improved beyond the existing SIP.
Global Structural Insulated Panels Market Dynamics
Market Drivers
- Growing demand for energy-efficient buildings drives the adoption of structural insulated panels
- Increasing construction activities in residential and commercial sectors boost market growth
- Rising government initiatives and building codes promoting sustainable construction fuel demand
- Advancements in SIP technology enhance durability, insulation, and structural integrity
Market Restraints
- High initial costs compared to traditional construction materials hinder widespread adoption
- Limited awareness and skilled workforce for SIP installation pose challenges
- Moisture sensitivity and potential for mold growth impact long-term performance
Market Opportunities
- Expansion of green building certifications and sustainable construction trends create growth avenues
- Increasing demand for prefabricated and modular construction enhances SIP market prospects
- Rising investments in infrastructure development in emerging economies drive new applications
Structural Insulated Panels Market Report Coverage
|
Market |
Structural Insulated Panels Market |
|---|---|
|
Structural Insulated Panels Market Size 2024 |
USD 13.6 Billion |
|
Structural Insulated Panels Market Forecast 2033 |
USD 24.1 Billion |
|
Structural Insulated Panels Market CAGR During 2025 - 2033 |
6.7% |
|
Structural Insulated Panels Market Analysis Period |
2021 - 2033 |
|
Structural Insulated Panels Market Base Year |
2024 |
|
Structural Insulated Panels Market Forecast Data |
2025 - 2033 |
|
Segments Covered |
By Product Type, By Sheathing Type, By Application, By End-User, and By Geography |
|
Regional Scope |
North America, Europe, Asia Pacific, Latin America, and Middle East & Africa |
|
Key Companies Profiled Aviation |
Future Building of America, Owens Corning, Foam Laminates, ACME PANEL, Enercept Inc., METECNO, Lattonedil Spa Milano, PFB Corporation, Kingspan Group, Eagle Panel Systems, Inc., Cornerstone Building Brands, and Foard Panel Inc. |
|
Report Coverage |
Market Trends, Drivers, Restraints, Competitive Analysis, Player Profiling, Covid-19 Analysis, Regulation Analysis |
Structural Insulated Panels Market Insights
The buildings that are built with these insulated boards, though, offer greater insulation and long-term cost-effectiveness. The constant separation provided by these panel's helps keep the wall temperature steady, which gives the occupant high comfort. It also decreases humidity accumulation on the wall and improves building surface longevity. The demand for structurally insulated panels is expected to increase through energy efficiency legislation and the initiatives taken by EU countries to reduce overall emissions from carbon in the region.
The construction and durability of isolation systems are key players in the sector panels. However, rising prices of plastics and wood materials are expected to hinder growth during the structural insulated panels market forecast period. Insulated polyurethane panels offer better temperature resistance and lightweight properties. The development of inexpensive and environmentally sensitive houses in rapid pace has put dream home into scope since the advent of building technologies. Since SIPs are already engineered panels, the facility of installation and speed are increased without affecting building quality. Wall assemblies installed in factories such as SIPs could minimize building time and operating cost by 40 to 48%.
Structural Insulated Panels Market Segmentation
The worldwide market for structural insulated panels is split based on product type, sheathing type, application, end-user, and geography.
Structural Insulated Panels (SIP) Market By Product Type
- Polystyrene
- Glass Wool
- Polyurethane
- Others
Polystyrene, namely expanded polystyrene (EPS), dominates the structural insulated panel (SIP) market. EPS is widely utilized because to its lightweight design, low cost, and excellent thermal insulation. It boasts high energy efficiency and moisture resistance, making it a popular choice for both residential and commercial structures. Furthermore, EPS SIPs are easier to handle, which reduces construction time and labor costs.
While polyurethane (PU) SIPs offer improved insulation and strength, their expensive cost prevents broad usage. Glass wool is utilized for fire resistance, although is less frequent in SIPs than polystyrene. Others, such as mineral wool and phenolic foam, have specialized purposes. Overall, EPS remains popular due to its cost, durability, and insulating performance.
Structural Insulated Panels (SIP) Market By Sheathing Type
- Oriented Strand Board (OSB)
- Plywood
- Sheet Metal
- Others
In the structural insulated panels (SIP) market, the most popular sheathing type is oriented strand board (OSB). Its dominance arises from its low cost, structural strength, and widespread availability. OSB is engineered to be both load-bearing and long-lasting, making it a great choice for residential and commercial construction. OSB is less expensive than plywood while providing comparable performance, which increases its popularity among builders. While sheet metal is durable and fire resistant, its use is limited due to high costs and specific industrial applications. The "Others" category, which includes fiber cement board and gypsum board, is for specific applications. OSB is still the preferred material for SIP sheathing due to its versatility and cost savings.
Structural Insulated Panels (SIP) Market By Application
- Walls
- Roofs
- Floors
According to structural insulated panels industry analysis, in 2024, the application for walls and floors represented the largest market share. An increasing need to renovate housing facilities due to better living standards and higher spending efficiency is likely to further stimulate the market growth of structural insulated panels. The increase in cold chain operations in major economies such as Asia-Pacific and North America due to the increasing consumption of processed and packaged food supply has driven the market for structural insulated panels. The reliability of well-built SIP houses has been shown to be similar to traditional buildings. Though, the failure of the structural insulated panel housing units can lead to poor installation procedures. Material and transport costs are the biggest challenges for SIP buildings. SIPs can be made more costly than conventional wood-framed buildings through extra material costs. In contrast, transport costs can be multiple times higher in comparison to traditional building goods for panelized products. These incremental costs can, however, be fully compensated by saving the cost on-site.
Structural Insulated Panels (SIP) Market By End-User
- Residential
- Commercial
- Non-Building
Due to the similarities in materials and construction practices, the life expectancy of a well-designed and well-kept SIP house is equivalent to a conventionally constructed home. These panels are produced according to application and thermal / structural requirements in different dimensions and thicknesses. Non-residential sector dominated the global SIP market and is projected to show similar trend over the forecast period. Residential sector is also anticipated to show significant growth over the structural insulated panels (SIP) market forecast period owing to green building initiatives by various regulatory bodies across Asia, Americas, and Europe.
Structural Insulated Panels Market Regional Outlook
North America
- S.
- Canada
Europe
- K.
- Germany
- France
- Spain
- Rest of Europe
Asia-Pacific
- India
- Japan
- China
- Australia
- South Korea
- Rest of Asia-Pacific
Latin America
- Brazil
- Mexico
- Rest of LATAM
The Middle East & Africa
- South Africa
- GCC Countries
- Rest of the Middle East & Africa (ME&A)
Structural Insulated Panels Market Regional Analysis
North America is the largest market for structural insulated panels, owing to high demand in residential and commercial construction, strict energy-efficiency standards, and a strong presence of significant producers. The Asia-Pacific region is the fastest-growing market, driven by urbanization, growing awareness of green buildings, and government measures to promote energy-efficient construction. Countries such as China, India, and Japan are increasingly using SIPs as a long-term replacement to traditional materials.
There are four major SIP companies in Canada and a number of small businesses. Local building authorities consider technologies differently, but it was generally good when more information was provided. In Canada, an SIP building can be built and building code clearance can still be received. Also, as an alternative construction material for residential and light-commercial buildings in the UK, structural insulated panels (SIPs) slowly gain in popularity. People believe that in contrast with standard timber frame construction, they show significant power, thermal efficiency, and deployment speed advantages. During the design of many kinds of panel construction systems, panels consisting of a thick layer of foam sandwiched between the two layers of the guided strand board (OSB) or plated surface are generally referred to as SIP. To Britain, the idea was relatively unknown, but its popularity in other nations, especially in the United States and Canada, inspired British designers and suppliers to join.
Structural Insulated Panels Market Players
Some of the top structural insulated panels market companies offered in our report include Future Building of America, Owens Corning, Foam Laminates, ACME PANEL, Enercept Inc., METECNO, Lattonedil Spa Milano, PFB Corporation, Kingspan Group, Eagle Panel Systems, Inc., Cornerstone Building Brands, and Foard Panel Inc.
Looking for discounts, bulk pricing, or custom solutions? Contact us today at sales@acumenresearchandconsulting.com
Frequently Asked Questions
Other Construction and Manufacturing Reports
September 2023
November 2023
April 2020
August 2020