
Implantable Medical Devices Market Size, Share, Report 2026 To 2035
Implantable Medical Devices Market (By Product Type: Cardiovascular Implants, Orthopedic Implants, Dental Implants, Neurological Implants, Ophthalmic Implants, Cosmetic & Reconstructive Implants, Drug Delivery & Other Implants; By Material Type: Metallic Implants, Polymer Implants, Ceramic Implants, Biologic & Bioabsorbable Implants; By End User: Hospitals, Ambulatory Surgical Centers (ASCs), Specialty Clinics, Academic & Research Institutes) - Global Industry Analysis, Size, Share, Regional Analysis, Trends and Forecast 2026 - 2035
- Last Updated: 08 Jun 2026
- Report Code: ARC1639
- Category: Healthcare and Pharmaceuticals
Implantable Medical Devices Market Size, Forecast 2026 To 2035
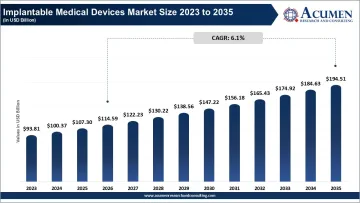
The global implantable medical devices market size reached at USD 107.30 billion in 2025, projecting growth to USD 194.51 billion by 2035 with a CAGR of 6.1% from 2026 to 2035. The overall rising emphasis on minimally invasive medical processes that are associated with joint replacement and cochlear act as a massive opportunity for the market.
Report Highlights
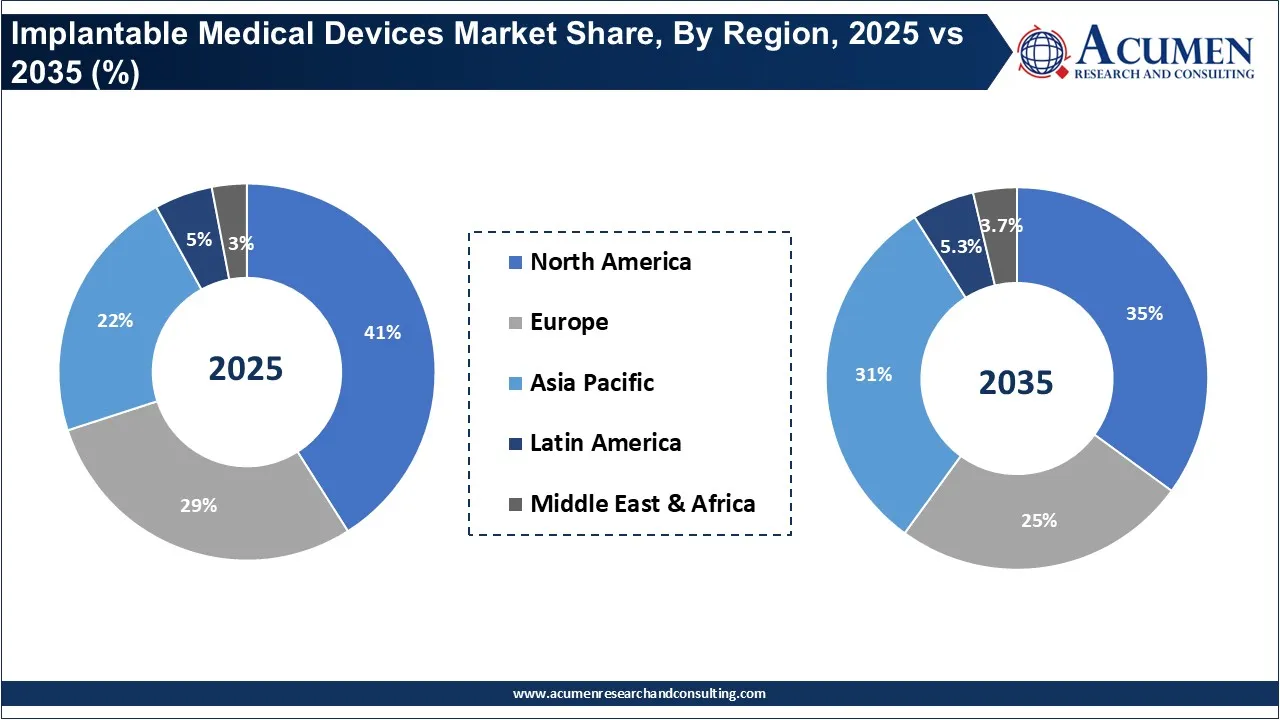
- By region, North America dominated the implantable medical devices market at 41% share in 2025, owing to factors such as an advanced healthcare system, high healthcare spending, significant presence of established medical device manufacturers, and demand for advanced technology implants.
- By region, Asia Pacific is estimated to register a CAGR of more than 10.2% for the forecast period of 2026-2035 owing to broadening healthcare access, increasing medical tourism, growing aged population and rising investments in healthcare infrastructure across countries like China, India, and South Asian nations.
- By product type, the cardiovascular implants generated largest share of 32% in 2025 owing to rising prevalence of cardiovascular diseases and increasing number of cardiac surgeries globally. Growing usage of devices such as pacemakers, stents and heart valve implants further supplemented the segment.
- By product type, the orthopaedic implants segment held the second largest share of 26% in 2025 owing to rising emphasis over minimally invasive surgeries.
- By material type, in 2025, metallic biomaterial captured a market share of around 52% due to its excellent strength, durability and corrosion resistance which are essential for long-term medical applications, also considered biocompatible with the human body.
- By material type, the biologic and bioabsorbable implants segment is seen to grow at CAGR of 9.7% during the forecast period owing to the rising initiatives for sustainable materials and shift in regulatory mandates.
- By end user, the hospitals segment led the market with 62% owing to the rising adoption of neurological implants and cardiovascular implants due to larger pool of patients.
- By end user, the ambulatory surgical centers segment held second largest share of 18% as they reduce the overall stress of patient monitoring that is highly required in such centers.
Top Government Initiatives
| Country | Government Initiative | Key Highlights |
|---|---|---|
| United States | FDA Breakthrough Devices Program | Accelerates approval and commercialization of innovative implantable medical technologies and life-saving devices. |
| China | Healthy China 2030 Initiative | Promotes healthcare modernization, advanced medical technologies, and domestic medical device manufacturing. |
| China | Made in China 2025 | Encourages local production and technological innovation in high-end medical devices and implant technologies. |
| India | Production Linked Incentive (PLI) Scheme for Medical Devices | Supports domestic manufacturing of medical devices and reduces dependence on imports. |
| India | Ayushman Bharat Healthcare Program | Expands healthcare access and increases demand for advanced surgical and implant procedures. |
| Japan | Society 5.0 Healthcare Innovation Program | Promotes AI-integrated healthcare technologies, robotics, and advanced implantable medical solutions. |
| Germany | Medical Technology Innovation Funding Programs | Supports R&D in minimally invasive surgical devices and next-generation implantable technologies. |
Market Dynamics
Market Drivers
Increasing prevalence of chronic diseases requiring implantable devices
The rising incidence of chronic diseases like cardiovascular disorders, orthopedic conditions, neurological diseases and diabetes, is a major factor in driving demand for implantable medical devices globally. Ageing population, sedentary lifestyle, obesity, increased healthcare awareness, all contributed to the increasing number of patients requiring long-term therapy, monitoring systems such as pacemakers, orthopedic implants, neurostimulators, implantable drug delivery systems and others. Besides, the escalating rate of cardiovascular diseases and joints degenerating is pushing surgical processes that require advanced implantable devices.
Advancements in technology enabling superior safety and performance
Constant innovations in materials, miniaturization, wireless connectivity and intelligent sensor integration technologies are enhancing the safety, durability and efficiency of implantable medical devices. Innovative solutions like AI assisted monitoring, bioabsorbable implants, 3D implantable devices, less invasive surgical interventions were helping in the enhancement of patients’ outcomes, reduction in recovery duration and physician’s confidence and acceptance of implantable devices in multiple applications.
Market Restraints
High cost of implantable medical devices limiting accessibility
The high costs associated with manufacturing, integration of advance technology and the surgery of implantable medical devices may limit their accessibility in the low and middle income economies. Additional costs associated with implantation surgery, post-surgery care, device monitoring and maintenance create a burden on healthcare systems and patient. Limited reimbursement for certain applications restricts the uptake and acceptance of advance implantable technologies.
Stringent regulatory requirements hindering product approvals
The product approvals process is a challenging and lengthy phase, as it requires stringent validation of the device to confirm patient safety and the device efficiency in long-term. Regulatory bodies such as the FDA and EU agencies impose very stringent rules and regulation for implantable device. The duration for product approval can extend from a couple of months to more than two years and the manufacturing cost associated with product approval process.
Market Opportunities
Increasing use of smart and bioabsorbable implantable devices
The growing adoption of bioabsorbable and smart implantable devices is contributing a substantial opportunity to market. Smart implants could offer advanced tracking and communication with physician and also predict patient behavior by analyzing gathered information on a continuous basis, thus offering customized treatment approach for various diseases. Bioabsorbable implants eliminate the need for surgical removal, which has a positive impact on overall patient care.
Growing untapped potential in emerging economies
Emerging economies offer substantial growth opportunities due to their expanding healthcare expenditure, improving healthcare infrastructure and rising medical tourism, as well as increasing knowledge about advancement in therapy. Investment made by the governments on healthcare facilities coupled with the availability of cost-effective medical treatments are spurring the demand for implantable medical devices across these regions.
Regional Insights
North America Implantable Medical Devices Market Analysis
North America represented the largest portion of 41% share in the global implantable medical devices market in 2025, driven by a robust presence of major medical device manufacturers, well-developed healthcare infrastructure, and rapid technological developments in next-generation implantable solutions. The region has a widespread adoption of various innovative implantable technologies such as smart implants, minimally invasive cardiac devices, neurostimulators, orthopedic implants and AI-driven monitoring devices that are influencing physician acceptance and patient outcomes.
“According to the U.S. Department of Health and Human Services, almost 129 million people in the U.S. Are afflicted with one or more major chronic conditions, including heart disease, hypertension, diabetes, cancer or obesity. An increasing elderly population and the surge in the number of surgical procedures being performed globally are accelerating the usage of implantable devices in hospitals and specialized care centers.”
United States Market Analysis
The U.S. Represents the largest segment within the North America implantable medical devices market. It exhibits a well-developed healthcare system and is considered to be a significant market due to its supportive regulatory landscape and a widespread usage of technically superior implants. With a huge patient population affected with various cardiac diseases, orthopedic abnormalities, and neurological conditions, demand for pacemakers, stents, spinal implants and orthopedic devices will rise.
Asia Pacific Implantable Medical Devices Market Analysis
The Asia Pacific region is predicted to grow the fastest rate of 10.2% CAGR in the global implantable medical devices market during the forecast period because of continuous improvement of health infrastructure, rising healthcare spending, rising disposable incomes, and a vast potential customer base. Due to the keen interest from domestic and international manufacturers of medical devices aiming to augment production facilities and distribution channels and providing low-cost implantable technologies to fit with local medical needs, the market is experiencing a significant amount of investment.
The rising number of chronic diseases, aged population, and the growing awareness about different treatment solutions are boosting the demand for implantable devices in various countries including China, India, Japan, and South Korea. Apart from these, numerous governments are strongly investing in modernizing health systems, medical facilities, e-health, and local medical device manufacturing.
India Market Analysis
India is proving to be one of the fast-growing markets for implantable medical devices because of enhanced health access, proliferation of the private sector hospitals and increase in medical tourism. There is also a noticeable increasing demand for orthopedic implants, cardiac implants and dental implants in the country because of growing count of chronic diseases and growing elderly people. Increasing investment in manufacturing medical devices and enhancing health facilities will also fuel the growth of market.
Segmental Insights
Product Type Insights
The cardiovascular implants market held the largest share of the implantable medical devices market in 2025, contributing around 32% of the global market revenue. This segment was majorly driven by rising number of cardiovascular diseases, such as coronary artery disease, arrhythmias, heart failure, valvular disorders in the developed as well as emerging nations. An increase in the usage of the implantable cardiovascular devices like pacemakers, coronary stents, implantable cardioverter defibrillators (ICDs), and heart valve implants have positively contributed to the market growth.
Implantable Medical Devices Market Revenue Share, By Product Type, 2025 (%)
| Product Type | Revenue Share, 2025 (%) |
|---|---|
| Cardiovascular Implants | 32% |
| Orthopedic Implants | 26% |
| Dental Implants | 12% |
| Neurological Implants | 10% |
| Ophthalmic Implants | 6% |
| Cosmetic & Reconstructive Implants | 8% |
| Drug Delivery & Other Implants | 6% |
The orthopaedic implants market held the second-largest market share of 26% in 2025 and was mainly driven by rising number of patients suffering from osteoporosis, osteoarthritis, spinal disorders and sports-related injuries around the globe. An increased number of hip replacement, knee replacement, trauma fixation, and spinal implant surgeries continue to drive the growth of this segment. Medical service providers are gradually moving towards minimally invasive orthopaedic surgeries to reduce hospital stays, and increase speed of recovery.
Material Insights
The metallic biomaterials market dominated this material segment and accounted for approximately 52% of the total market in 2025. Metallic biomaterials, including titanium, stainless steel, cobalt-chromium alloys, and nitinol, accounted for the largest share of this segment owing to their enhanced mechanical strength, durability, corrosion resistance, and biocompatibility. These materials are widely used in cardiovascular, dental, spinal, and orthopedic implants due to their capacity to withstand continuous physiological stress for prolonged durations.
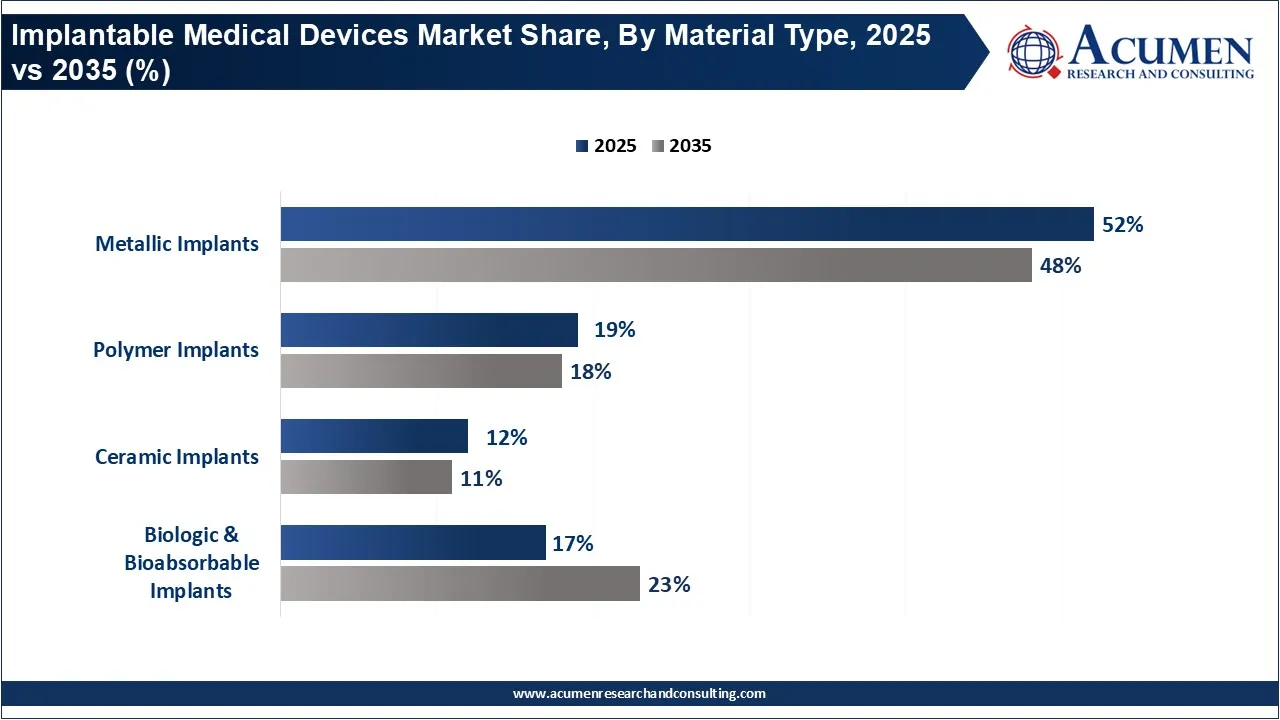
The biologics and bioabsorbable implants segment is estimated to expand at the highest CAGR of 9.7% during the forecast period, driven by the burgeoning demand for advanced future implant materials that have the potential to degrade over time once they have served their therapeutic application in the body. Biologic and bioabsorbable implants can preclude secondary explantation surgeries and potential long-term complications associated with permanently embedded implants.
End User Insights
The hospital segment held the largest share of implantable medical devices market, occupying almost 62% of the entire revenue share in 2025. It is considered the best platform for highly complex surgical implantation, such as cardiologic implantations, neurological implantations, orthopaedic implantations, and cochlear implantations, as hospitals possess sophisticated diagnostic setup, dedicated surgical teams, sophisticated intensive care unit (ICU) as well as post-operation caring facility.
Implantable Medical Devices Market Revenue Share, By End User, 2025 (%)
| End User | Revenue Share, 2025 (%) |
|---|---|
| Hospitals | 62% |
| Ambulatory Surgical Centers (ASCs) | 18% |
| Specialty Clinics | 14% |
| Academic & Research Institutes | 6% |
The ambulatory surgical centers segment held 18% of the second largest market share in 2025. The increasing need of performing outpatient surgical procedures that minimizes the cost of treatment, shortening the recovering period, also helps in performing surgery in minimal cost and shortest possible time, providing sufficient caring facility but minimizing the number of hospitalization days and hence avoidinghospitalacquired infection.
Key Players
- Medtronic
- Abbott Laboratories
- Johnson and Johnson
- Boston Scientific Corporation
- Smith & Nephew plc
- Stryker
- Cochlear Limited
- Integra LifeSciences
- LivaNova PLC
- Biotronik SE and Co. KG
Recent News
- In 2025, Abbott announced its dual chamber leadless pacemaker system-AVEIR DR-in India. It is world’s first dual chamber leadless pacemaker with wireless beat-to-beat communication within the heart and has the potential to revolutionize the field of minimally invasive cardiac implant technology.
- In 2025, Boston Scientific reached an agreement to purchase Nalu Medical, an innovator in battery-free neurostimulation technology for chronic pain management, for about USD 533 million to expand its neuromodulation implant portfolio.
Market Segmentation
By Product Type
- Cardiovascular Implants
- Orthopedic Implants
- Dental Implants
- Neurological Implants
- Ophthalmic Implants
- Cosmetic & Reconstructive Implants
- Drug Delivery & Other Implants
By Material Type
- Metallic Implants
- Polymer Implants
- Ceramic Implants
- Biologic & Bioabsorbable Implants
By End User
- Hospitals
- Ambulatory Surgical Centers (ASCs)
- Specialty Clinics
- Academic & Research Institutes
By Region
- North America
- Asia Pacific
- Europe
- Latin America
- Middle East & Africa
Looking for discounts, bulk pricing, or custom solutions? Contact us today at sales@acumenresearchandconsulting.com
Frequently Asked Questions
Other Healthcare and Pharmaceuticals Reports
October 2020
January 2025
February 2024
August 2022