
Surgical Navigation Systems Market Size, Share, Trends and Forecast 2026 To 2035
Surgical Navigation Systems Market (By Component: Software, Hardware, Services; By Tracking Technology: Electromagnetic Navigation, Optical Navigation, Hybrid Navigation, Others; By Navigation/Imaging Method: CT-Based Navigation, Fluoroscopy-Based Navigation, MRI-Based Navigation, Imageless Navigation, Ultrasound-Based Navigation, Multimodal/Image-Fusion Navigation, Others; By Application: Neurosurgery, Orthopedic Surgery, Spine Surgery, ENT Surgery, Dental & Maxillofacial Surgery, Others; By Procedure: Cranial Procedures, Spinal Procedures, Knee Procedures, Hip Procedures, Others; By System Configuration: Standalone Navigation Systems, Integrated Navigation Systems; By End User: Hospitals Ambulatory Surgical Centers, Specialty Clinics & Surgical Centers, Academic & Research Medical Centers, Others) - Global Industry Analysis, Size, Share, Regional Analysis, Trends and Forecast 2026 - 2035
- Last Updated: 21 Oct 2026
- Report Code: ARC2230
- Category: Healthcare and Pharmaceuticals
Surgical Navigation Systems Market Size and Forecast
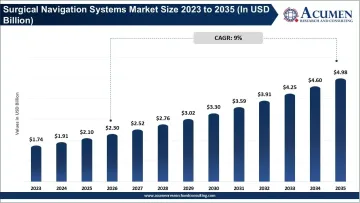
The global surgical navigation systems market size was valued at $2.10 billion in 2025 and is observed to reach at $4.98 billion by 2035; growing at a promising CAGR of 9% during the forecast period of 2026-2035. Rising adoption of minimally invasive procedures, increasing demand for precision-guided surgery, and growing integration of advanced imaging, electromagnetic and optical tracking, robotics, and AI are accelerating the adoption of surgical navigation systems across neurosurgery, orthopedics, spine, ENT, and other surgical specialties.
- Base Year Market Size (2025): $2.10 billion
- Current Year Market Size (2026): $2.30 billion
- Estimated Year Market Size (2035): $4.98 billion
- Forecast Period CAGR (2026-2035): 9.0%
Report Highlights
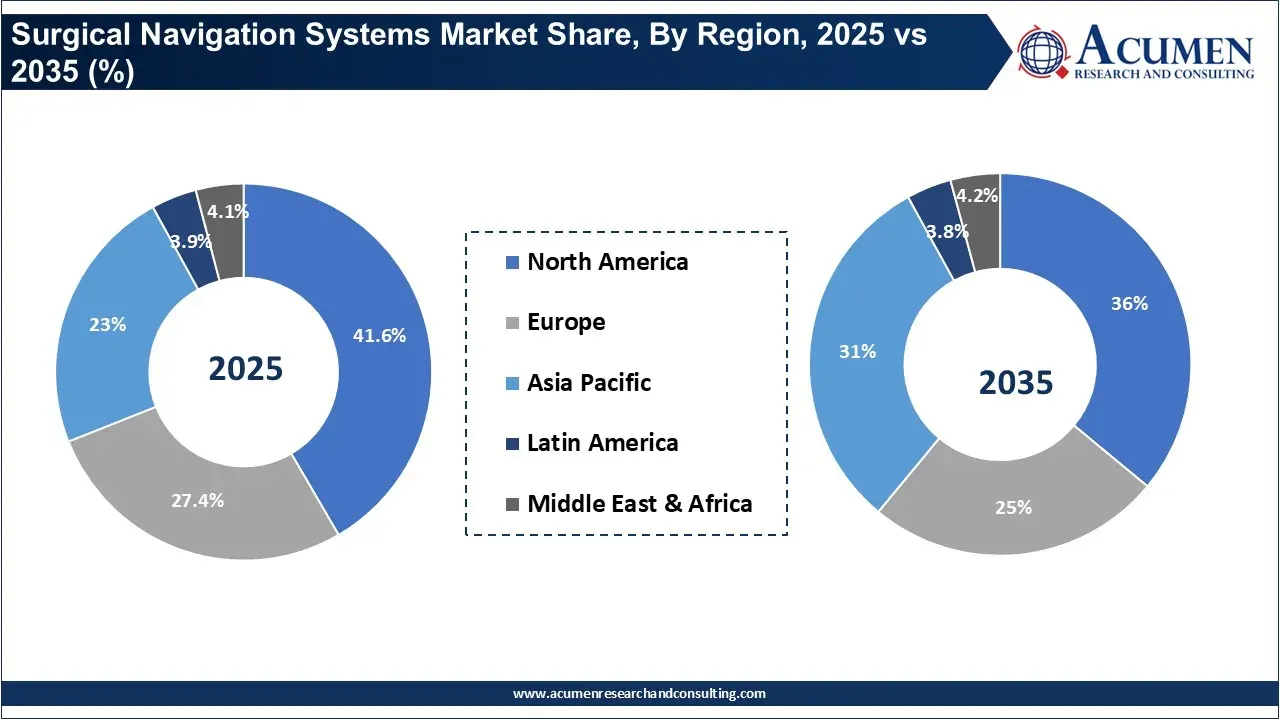
- By region: North America dominated the market with a 41.6% share in 2025, supported by advanced healthcare infrastructure, established adoption of image-guided surgery, and strong investment in surgical navigation and related technologies.
- By component: Hardware dominated the component segment with a 58.0% share in 2025, driven by demand for navigation workstations, tracking systems, imaging equipment, sensors, and specialized surgical instruments.
- By tracking technology: Electromagnetic navigation dominated the tracking technology segment with a 41.0% share in 2025, supported by its ability to track surgical instruments without requiring direct line of sight.
- By navigation/imaging method: CT-based navigation dominated the navigation/imaging method segment with a 29.0% share in 2025, driven by high-resolution anatomical imaging and established use across cranial, spinal, ENT, and orthopedic procedures.
- By application: Neurosurgery dominated the application segment with a 35.5% share in 2025, supported by the need for precise anatomical localization, trajectory planning, and instrument guidance during complex neurosurgical procedures.
- By procedure: Cranial procedures dominated the procedure segment with a 28.0% share in 2025, driven by the need for precise navigation around critical brain structures, tumors, and skull-base anatomy.
- By system configuration: Standalone navigation systems dominated the system configuration segment with a 57.0% share in 2025, supported by demand for dedicated navigation, tracking, image registration, and surgical guidance capabilities.
- By end user: Hospitals dominated the end-user segment with a 45.0% share in 2025, supported by high surgical volumes, advanced imaging infrastructure, specialized operating rooms, and multidisciplinary surgical capabilities.
What Are Surgical Navigation Systems? How is the Market Expanding?
Surgical navigation systems are computer-assisted systems which integrate patient imaging, tracking systems, patient and surgical field registration, surgical planning and real-time instrument position to enable surgeons guide complex surgical procedures. The technology is increasingly used in neurosurgical, orthopedic, spine, ENT, dental and maxillofacial procedures.
Market growth is being driven by patient demand for less invasive, precision-guided surgery, greater adoption of advanced imaging and image-fusion technologies and the integration of navigation into the wider operating room environment by implanting and minimally invasive surgeons and by tracking more than just instruments, assisting in planning and visualization, intraoperative guidance, and decision making.
Growth Factors
- Complex Procedures: Increasing complexity of neurosurgical, orthopedic, spinal, ENT, and other procedures is increasing demand for technologies that provide real-time anatomical guidance. Surgical navigation systems connect patient imaging with tracked instruments, helping surgeons plan trajectories and localize anatomy during procedures where precise positioning is critical.
- Minimally Invasive Surgery: Growing use of minimally invasive procedures is supporting adoption of navigation technologies that can improve visualization and instrument guidance while limiting unnecessary tissue disruption. Surgical navigation can integrate preoperative imaging and intraoperative tracking, supporting more precise approaches across orthopedic, spinal, neurological, ENT, and other procedures.
- Digital Operating Rooms: Increasing investment in digitally connected operating rooms is expanding opportunities for surgical navigation systems that integrate imaging, tracking, planning software, robotics, and visualization technologies. The convergence of these technologies is shifting navigation from standalone guidance toward broader procedure ecosystems supporting planning and intraoperative decision-making.
Market Dynamics
Key Drivers
- Real-Time Guidance: Surgical navigation systems provide continuous localization of instruments relative to patient anatomy and medical images, supporting surgeons during complex procedures. FDA-cleared navigation technologies demonstrate how tracked instruments can be registered against patient imaging and used to follow predefined surgical plans, strengthening demand for image-guided procedural workflows.
- Imaging Integration: Integration with CT, MRI, fluoroscopy, and other imaging technologies is expanding the capabilities of surgical navigation systems. Three-dimensional patient models and intraoperative imaging can provide surgeons with detailed anatomical information, while improved registration and visualization technologies support more accurate planning and guidance during procedures.
- Robotic Surgery: Increasing integration between navigation systems and robotic surgical platforms is creating demand for connected technologies that combine anatomical guidance, instrument tracking, planning, and robotic assistance. Computer-assisted surgical systems already encompass surgical navigation and robotic technologies, while newer platforms increasingly combine multiple digital capabilities within the operating room.
Market Restraints
- High System Costs: Surgical navigation platforms can require substantial investment in tracking equipment, imaging systems, workstations, specialized instruments, software, installation, and maintenance. The capital requirements can make adoption more difficult for hospitals with limited budgets, particularly when facilities also need to upgrade operating-room infrastructure to support advanced image-guided procedures.
- Training Requirements: Effective use of surgical navigation systems requires surgeons and operating-room personnel to understand registration, imaging workflows, instrument tracking, system calibration, and navigation software. Training requirements can increase implementation time and operating costs, while limited availability of experienced personnel can restrict adoption in hospitals without established image-guided surgery programs.
- Workflow Complexity: Integrating navigation into existing surgical workflows can introduce additional steps involving imaging acquisition, patient registration, equipment setup, calibration, and instrument tracking. Poorly integrated systems may increase procedure preparation time or disrupt established workflows, making usability and interoperability important considerations for hospitals evaluating navigation technology investments.
Market Opportunities
- AI Navigation: Artificial intelligence can enhance surgical navigation through automated image segmentation, anatomical recognition, registration, and real-time decision support. Current research is exploring AI-driven segmentation and deformation-field modeling to address limitations in navigation accuracy, creating opportunities for intelligent systems that can adapt navigation guidance to changing intraoperative conditions.
- Mixed Reality: Augmented and mixed reality technologies are creating opportunities to display navigation information directly within the surgeon's field of view. FDA records include cleared orthopedic augmented-reality navigation technologies, while clinical research has reported applications across neurosurgery, spinal surgery, oral and maxillofacial surgery, and orthopedics.
- Portable Systems: Development of compact and portable navigation platforms can expand access beyond large tertiary hospitals and specialized operating rooms. Research identifies lightweight and portable systems as an important future direction, potentially enabling navigation-assisted procedures in more diverse clinical environments while reducing infrastructure requirements associated with conventional platforms.
Key Challenges
- Registration Accuracy: Accurate registration between preoperative images, patient anatomy, and tracked instruments is essential for reliable navigation. Small registration errors can affect surgical guidance, while changes in patient positioning or anatomy can further reduce accuracy. Improving registration techniques therefore remains a key technical challenge, particularly for complex procedures.
- Tissue Deformation: Navigation is particularly challenging when soft tissues move or deform during surgery because preoperative images may no longer accurately represent the patient's intraoperative anatomy. Respiratory movement, tissue displacement, surgical manipulation, and other changes can reduce navigation reliability, creating demand for real-time imaging and advanced deformation modeling.
- Clinical Integration: Navigation systems must work reliably with imaging equipment, surgical instruments, hospital IT infrastructure, operating-room workflows, and other digital technologies. Interoperability, cybersecurity, usability, and clinical validation can complicate deployment, while healthcare providers must ensure that technology supports rather than disrupts surgeon-controlled decision-making and established procedural workflows.
Surgical Navigation Systems Market Segmentation Insights
Component Insights
Hardware: Hardware dominated the component segment with 58.0% share in 2025, driven by demand for navigation workstations, tracking systems, imaging equipment, surgical instruments, cameras, sensors, and other physical infrastructure required for computer-assisted surgery. Hospitals and surgical centers continue investing in hardware-enabled navigation platforms to improve anatomical visualization, instrument positioning, and procedural precision.
Software: Software represented the second-largest component category with 27.0% share in 2025, supported by increasing use of surgical planning, image processing, anatomical visualization, navigation, registration, and clinical decision-support applications. Software is also becoming increasingly important as navigation platforms incorporate AI, 3D visualization, image fusion, and data-driven surgical workflows.
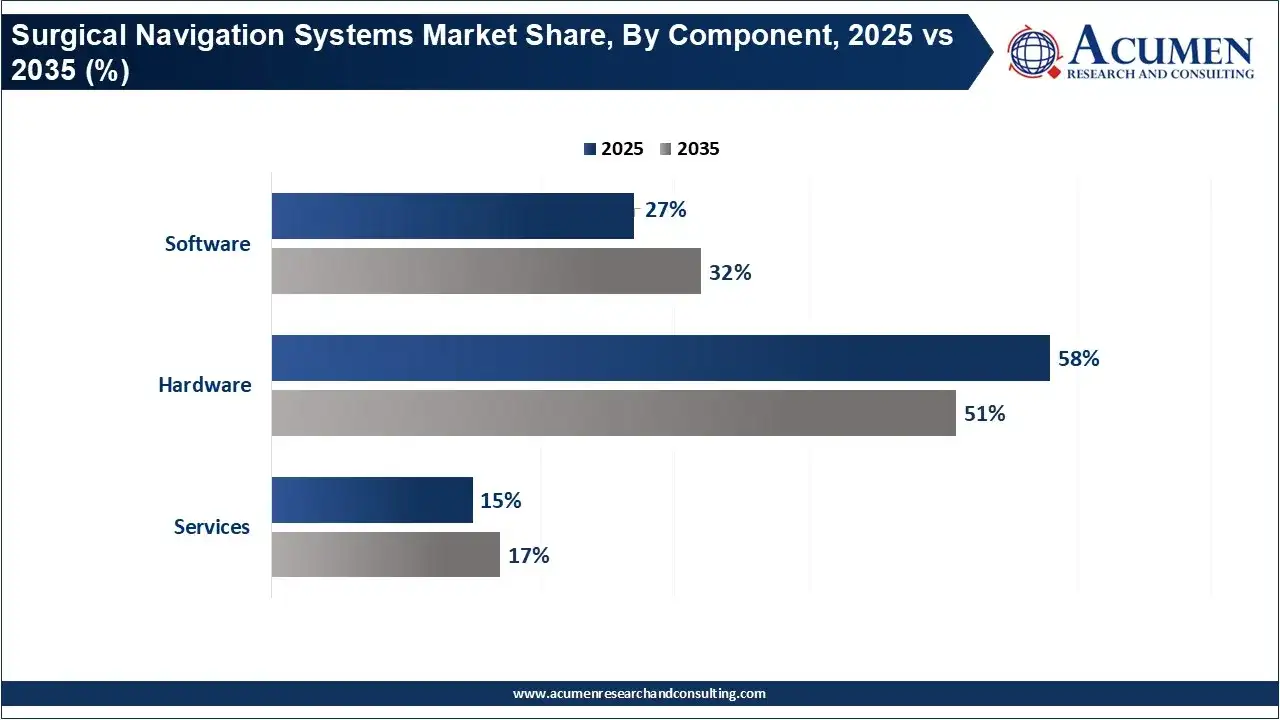
Services: Services accounted for 15.0% share in 2025, supported by requirements for system installation, integration, training, maintenance, technical support, software upgrades, and workflow optimization. As navigation systems become more technologically sophisticated, healthcare providers increasingly require specialized services to maintain system performance and integrate navigation technologies into existing operating-room infrastructure.
Tracking Technology Insights
Electromagnetic Navigation: Electromagnetic navigation dominated the tracking technology segment with 41.0% share in 2025, supported by its ability to track surgical instruments without requiring direct line of sight between the instrument and tracking camera. This capability supports navigation in complex anatomical environments and contributes to adoption across ENT, neurosurgery, spine, and minimally invasive procedures.
Hybrid Navigation: Hybrid navigation is projected to be the fastest-growing tracking technology, at a 10.5% CAGR from 2026 to 2035, supported by the ability to combine multiple tracking approaches and imaging technologies within a single surgical workflow. Hybrid configurations can improve flexibility across complex procedures by integrating complementary navigation capabilities, imaging information, and instrument tracking.
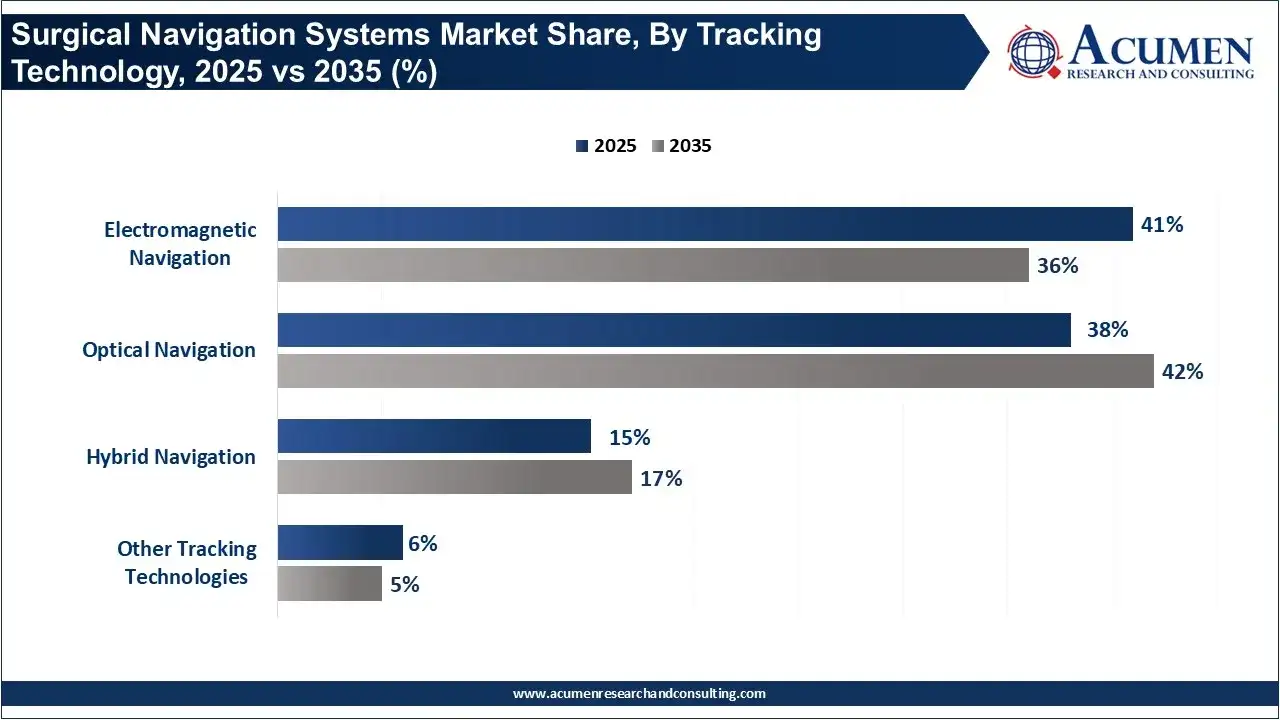
Optical Navigation: Optical navigation represented the second-largest tracking technology category with 38.0% share in 2025, supported by established infrared tracking capabilities, high instrument-tracking precision, and widespread use in image-guided surgical procedures. Optical systems remain important across neurosurgery, spine, orthopedic, and ENT applications where accurate instrument localization and real-time positional information are required.
Navigation/Imaging Method Insights
CT-Based Navigation: CT-based navigation dominated the navigation/imaging method segment with 29.0% share in 2025, supported by the high-resolution anatomical information provided by computed tomography and its established use in cranial, spinal, ENT, and orthopedic procedures. CT-based systems enable patient-specific surgical planning and image-guided instrument positioning across procedures involving complex bony and anatomical structures.
Multimodal/Image-Fusion Navigation: Multimodal/image-fusion navigation is positioned as the fastest-growing method based on its increase from 9.0% share in 2025 to 14.0% by 2035, supported by the ability to combine information from CT, MRI, ultrasound, and other imaging modalities. Image fusion provides surgeons with more comprehensive anatomical information and supports increasingly complex procedures requiring multimodal visualization.
Fluoroscopy-Based Navigation: Fluoroscopy-based navigation represented the second-largest category with 21.0% share in 2025, supported by its established role in real-time intraoperative imaging, particularly across spine, orthopedic, and other procedures requiring continuous visualization of anatomical structures and instrument positioning. Its integration with navigation platforms enables surgeons to combine imaging feedback with computer-assisted guidance.
Imageless Navigation: Imageless navigation accounted for 17.0% share in 2025, supported by workflows that use anatomical landmarks, preoperative data, tracking technologies, and computational models without continuous reliance on intraoperative imaging. The approach can reduce imaging requirements during selected procedures while supporting navigation in operating rooms where streamlined workflows and lower imaging dependence are priorities.
Application Insights
Neurosurgery: Neurosurgery dominated the application segment with 35.5% share in 2025, supported by the critical need for precise anatomical localization, trajectory planning, and instrument guidance during complex cranial and brain procedures. Surgical navigation helps neurosurgeons correlate preoperative imaging with patient anatomy and supports accurate approaches around sensitive neurological structures.
Orthopedic Surgery: Orthopedic surgery represented the second-largest application category with 25.5% share in 2025, supported by growing use of computer-assisted technologies for implant positioning, anatomical alignment, surgical planning, and intraoperative guidance. Navigation systems are increasingly integrated into orthopedic workflows involving joint replacement, complex bone procedures, and precision-focused interventions.
Spine Surgery: Spine surgery accounted for 17.0% share in 2025, supported by increasing use of navigation for pedicle screw placement, spinal alignment, trajectory planning, and intraoperative verification. The ability to improve visualization of spinal anatomy and guide instruments around critical structures supports adoption across complex and minimally invasive spinal procedures.
Procedure Insights
Cranial Procedures: Cranial procedures dominated the procedure segment with 28.0% share in 2025, supported by the need for highly precise navigation around the brain, skull base, tumors, and critical neurological structures. Navigation systems provide patient-specific anatomical guidance that assists surgeons with trajectory planning, lesion localization, and instrument positioning during complex cranial interventions.
Spinal Procedures: Spinal procedures represented the second-largest category with 22.0% share in 2025, supported by growing adoption of image-guided technologies for spinal instrumentation, pedicle screw placement, deformity correction, and minimally invasive surgery. Navigation can improve visualization and intraoperative guidance where precise instrument trajectories are required around the spinal cord and surrounding structures.
Knee Procedures: Knee procedures accounted for 17.0% share in 2025, supported by increasing use of computer-assisted navigation for alignment, implant positioning, and intraoperative assessment during knee replacement and other orthopedic interventions. Navigation technologies can provide surgeons with real-time positional information to support accurate execution of planned procedures.
System Configuration Insights
Standalone Navigation Systems: Standalone navigation systems dominated the system configuration segment with 57.0% share in 2025, supported by demand for dedicated navigation platforms that provide specialized tracking, visualization, image registration, and surgical guidance capabilities. These systems allow healthcare providers to deploy navigation independently across applicable surgical procedures without requiring complete integration with broader robotic or operating-room platforms.
Integrated Navigation Systems: Integrated navigation systems represented the second-largest configuration with 43.0% share in 2025, supported by increasing convergence between surgical navigation, robotics, imaging, operating-room equipment, and digital surgical platforms. Integrated systems can streamline information exchange across technologies and enable surgeons to access navigation, imaging, planning, and guidance capabilities through connected workflows.
End User Insights
Hospitals: Hospitals dominated the end-user segment with 45.0% share in 2025, supported by higher surgical volumes, availability of specialized operating rooms, advanced imaging infrastructure, and access to multidisciplinary surgical teams. Large hospitals and tertiary medical centers are major adopters of navigation systems because they perform complex neurosurgical, orthopedic, spine, ENT, and other image-guided procedures.
Ambulatory Surgical Centers: Ambulatory surgical centers represented the second-largest end-user category with 23.0% share in 2025, supported by the expansion of outpatient and minimally invasive procedures. Increasing demand for efficient surgical workflows is encouraging selected centers to adopt navigation technologies that can improve procedural guidance while supporting shorter, technology-enabled surgical pathways.
Surgical Navigation Systems Market Regional Insights
North America Surgical Navigation Systems Market: Established Clinical Infrastructure Drives Regional Dominance
North America dominated the surgical navigation systems market with a 41.60% share in 2025, valued at $0.87 billion, supported by advanced hospital infrastructure, high adoption of image-guided surgery, strong neurosurgical and orthopedic capabilities, and continued investment in robotic and navigation-assisted procedures. The region is projected to reach $1.79 billion by 2035, expanding at a 7.2% CAGR from 2026 to 2035.
The United States represents the leading country in the region, supported by a large installed base of advanced surgical systems, high healthcare technology spending, established medical-device manufacturers, and increasing integration of navigation with robotics, intraoperative imaging, and AI-enabled surgical planning. Canada also contributes through investments in advanced surgical infrastructure, academic medical centers, and image-guided procedures.
- United States: Leads regional adoption due to extensive use of image-guided neurosurgery, spine surgery, orthopedic procedures, robotic surgery, and advanced intraoperative imaging technologies.
- Canada: Expanding adoption through investments in tertiary hospitals, academic medical centers, minimally invasive surgery, and advanced surgical visualization and navigation infrastructure.
Asia-Pacific Surgical Navigation Systems Market: Rapid Technology Adoption Accelerates Regional Growth
Asia-Pacific is anticipated to be the fastest growing regional market, estimated to grow at a CAGR of 12.6% from 2026 to 2035. The regional market is anticipated to grow from $0.53 billion in 2026 to reach $1.55 billion by 2035.
Growth is driven by rapid upgrade of hospitals, progress in the field of minimal invasive surgeries, rising volume of surgeries, technological upgrades and innovation, and increasing investment and increasing volume of investments by big medtech players in the region, particularly in robotic and image guided surgery. China, Japan, South Korea and India are among the major countries driving the adoption of surgical navigation and robotics in the region.
- China: Accelerates adoption via health-care reform and upgradation, development of technologically sophisticated surgery centers, development of in-house medical devices and robotics and image-guided surgeries.
- Japan: Hospital infrastructure, at a very high level; latest surgical robots and more focused on precision image-guided procedures.
Top 5 Countries & Their Investment Statistics
- United States: U.S. healthcare providers and medical-device companies continue to invest heavily in image-guided surgery, surgical robotics, intraoperative imaging, and navigation infrastructure. Investment is increasingly shifting toward integrated platforms that combine navigation with robotics, imaging, AI, and surgical planning.
- Germany: Germany has a strong surgical-navigation ecosystem centered around medtech R&D, digital surgery, and advanced hospital infrastructure. Brainlab's €200 million IPO fundraising in 2025 provides a significant example of capital raised by a major surgical-navigation technology company for business expansion and technology development.
- China: Chinese investment is increasingly focused on domestic development of surgical robotics, medical imaging, navigation platforms, and AI-enabled medical devices. Government support for high-end medical equipment and domestic innovation is encouraging hospitals and manufacturers to expand advanced surgical-technology capabilities.
- Japan: Japanese hospitals and research institutions continue investing in advanced image-guided and robot-assisted surgery. Procurement programs at major medical institutions include investments in intraoperative navigation and robot-assisted surgical-navigation systems, supporting the modernization of specialized surgical infrastructure.
- India: Investment is increasing in indigenous surgical-navigation technology, particularly across cranial, spine, and ENT procedures. HRS Navigation raised $5 million in Pre-Series A funding, with the capital supporting product development, manufacturing, global expansion, and next-generation navigation technologies.
Technology Intelligence
| Technology | Major Applications | Key Advantages |
|---|---|---|
| Optical Navigation | Neurosurgery, spine, orthopedic surgery, ENT | High tracking accuracy and established clinical use |
| Electromagnetic Navigation | ENT, neurosurgery, minimally invasive procedures | Does not require direct line of sight |
| Image-Guided Navigation | Brain, spine, ENT, orthopedic procedures | Provides patient-specific anatomical guidance |
| AI-Enabled Navigation | Tumor surgery, anatomical identification, surgical planning | Automated analysis and decision-support capabilities |
| Robotic Navigation | Spine, cranial and orthopedic procedures | High precision and repeatability |
| Mixed Reality Navigation | Spine, cranial and minimally invasive procedures | Reduces need to shift attention between anatomy and navigation displays |
| 3D Navigation | Neurosurgery, spine, ENT, orthopedic surgery | Improves visualization of complex anatomy |
| Hybrid Navigation | Complex multidisciplinary surgery | Provides greater flexibility and multimodal information |
Top Companies
- Medtronic plc
- Brainlab SE
- Stryker Corporation
- Zimmer Biomet Holdings, Inc.
- Siemens Healthineers AG
- Johnson & Johnson MedTech
- Smith+Nephew plc
- B. Braun Melsungen AG
- KARL STORZ SE & Co. KG
- Globus Medical, Inc.
Partnerships, Launches & Innovations
- April 2026: GE HealthCare and Medtronic announced digital integration between GE HealthCare's bkActiv intraoperative ultrasound system and Medtronic's Stealth AXiS surgical navigation system. The integration combines real-time intraoperative ultrasound with planning, navigation, and robotics to support cranial procedures and create a more unified surgical workflow.
- February 2026: Medtronic received U.S. FDA clearance for its Stealth AXiS surgical system, an integrated platform combining surgical planning, navigation, and robotics for spine surgery. The platform is designed to provide a unified workflow and has an architecture intended to support future cranial and ENT applications subject to regulatory clearance.
Segments Covered
By Component
- Software
- Hardware
- Services
By Tracking Technology
- Electromagnetic Navigation
- Optical Navigation
- Hybrid Navigation
- Others
By Navigation/Imaging Method
- CT-Based Navigation
- Fluoroscopy-Based Navigation
- MRI-Based Navigation
- Imageless Navigation
- Ultrasound-Based Navigation
- Multimodal/Image-Fusion Navigation
- Others
By Application
- Neurosurgery
- Orthopedic Surgery
- Spine Surgery
- ENT Surgery
- Dental & Maxillofacial Surgery
- Others
By Procedure
- Cranial Procedures
- Spinal Procedures
- Knee Procedures
- Hip Procedures
- ENT & Skull Base Procedures
- Dental & Maxillofacial Procedures
- Others
By System Configuration
- Standalone Navigation Systems
- Integrated Navigation Systems
By End User
- Hospitals
- Ambulatory Surgical Centers
- Specialty Clinics & Surgical Centers
- Academic & Research Medical Centers
- Others
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East & Africa
Looking for discounts, bulk pricing, or custom solutions? Contact us today at sales@acumenresearchandconsulting.com
Frequently Asked Questions
Related Market Research Reports
October 2026
May 2023
June 2022
October 2021
February 2025
April 2021
March 2021
December 2020