
Frozen Food Market Size, Share, Trends, Forecast 2026 To 2035
Frozen Food Market (By Product Type: Ready Meals, Fruits & Vegetables, Meat & Poultry, Seafood, Bakery Products, Snacks & Appetizers, Desserts & Ice Cream, Others; By Food Category: Vegetarian, Non-Vegetarian; By Packaging Type: Bags & Pouches, Boxes & Cartons, Trays, Tubs & Cups, Others; By Distribution Channel: Supermarkets & Hypermarkets, Convenience Stores, Specialty Stores, Online Retail, Foodservice; By End User: Household, Commercial Foodservice, Institutional) - Global Industry Analysis, Size, Share, Growth, Trends, Regional Analysis And Forecast 2026 To 2035
- Last Updated: 09 Jul 2026
- Report Code: ARC463
- Category: Consumer Goods and Food and Beverages
Frozen Food Market Size, Forecast 2026 To 2035
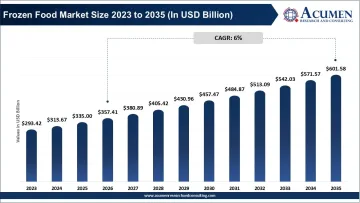
The global frozen food market size accounted for USD 335 billion in 2025 and is projected to reach around USD 601.58 billion by 2035, growing at a CAGR of 6% during the forecast period from 2026 to 2035. Continuous investments in cold chain logistics, refrigerated transportation, and online grocery platforms are improving the accessibility and availability of frozen food products across both developed and emerging markets. The rapid growth of supermarkets, quick-commerce platforms, and digital grocery retailers is enabling consumers to purchase frozen foods more conveniently than ever before.
Report Highlights
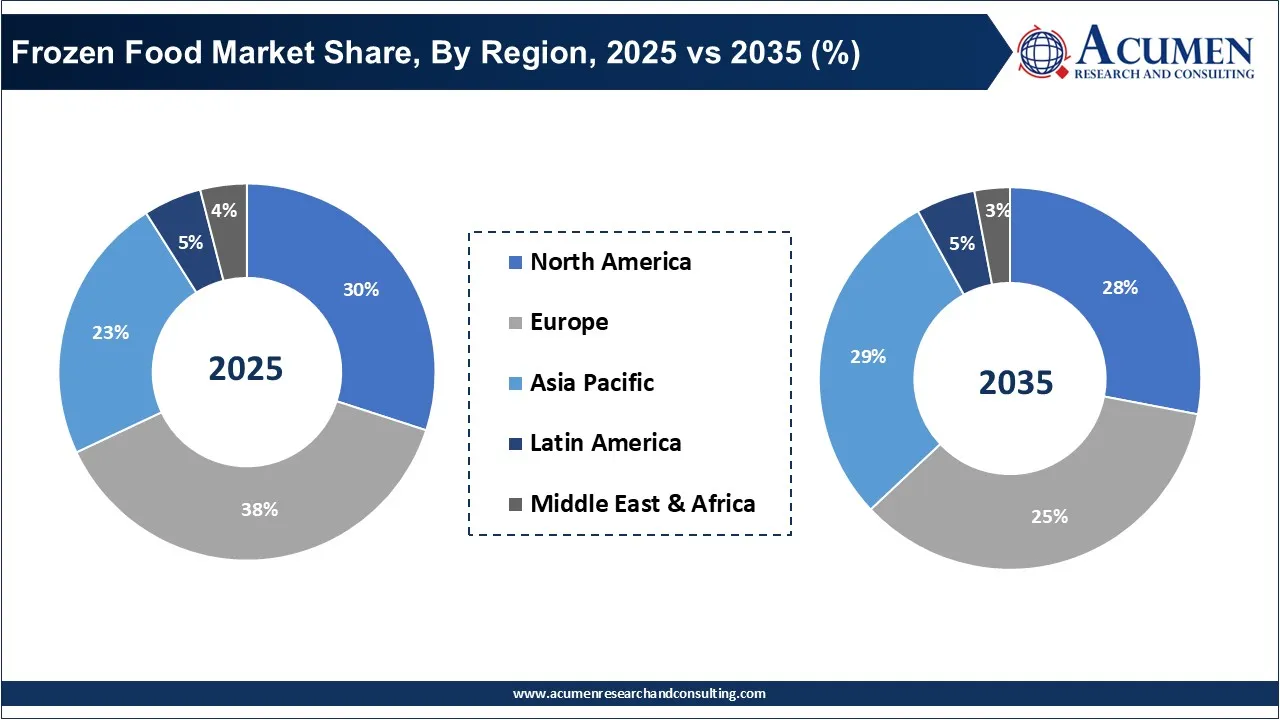
- By region, Europe accounted for the largest market share of 38.0% in 2025 and is predicted to occupy 35.0% in 2035, exhibiting a CAGR of 5.0% from 2026 to 2035, owing to a robust infrastructure of distribution and freezing, mature retail network, and high demand for quick and easy meal options.
- By region, Asia Pacific is emerging as the fastest-growing region and was anticipated to capture 23.0% market share in 2025 and 29.0% by 2035, growing at a robust CAGR of 8.7% in the forecast period, owing to rapidly urbanizing population, growing purchasing power, and expansion of retail outlets in urban as well as semi-urban areas.
- By product type, the ready meals grabbed the biggest market share in 2025 at 29.0%, predicted to reach 31.0% in 2035 due to increase in preference for easy-to-prepare, save time meal and grab-and-go meal options.
- By product type, meat & poultry secured the second largest position in the market in 2025 with a share of 20.0%, supported by a rise in consumer preference for frozen animal protein products and increasing use by QSRs.
- By food category, non-vegetarian is the largest market with a 68.0% share in 2025, expected to reach 64.0% in 2035 at a CAGR of 5.2%, attributed to the massive global consumption of frozen meat, chicken and seafood.
- By food category, vegetarian is the fastest expanding segment with 32.0% market share in 2025, forecast to touch 36.0% by 2035 at a CAGR of 7.4%, supported by expanding trends of plant-based and flexitarian eating patterns worldwide.
- By packaging type, bags & pouches led the frozen food market with 42.0% market share in 2025, as they are light in weight, low cost, offer good protection to food, have resealable properties, and take up less space in storing and shelving compared to the other packaging solutions.
- By packaging type, boxes & cartons was the second most popular packaging solution holding 28.0% of the market share in 2025, owing to their inherent strength, product protection capabilities, space for branding, and rise in use of recyclables in this packaging.
- By distribution channel, supermarkets & hypermarkets dominated the market with a 52.0% share in 2025, as these offer wide selection of products, large capacity for storage of refrigerated & frozen food, display boards, discounts and promotions.
- By distribution channel, convenience stores had a market share of 15.0% in 2025 and is predicted to increase by 17.0% by 2035, owing to increased accessibility and greater convenience in purchase as many consumers visit convenience stores to buy their daily items and small amount of food items.
- By end user, household remained the dominant segment with a 67.0% share in 2025, and the trend is anticipated to continue till 2035, which can be ascribed to the increase in number of freezer units and working professionals across households and their convenience-seeking nature.
- By end user, commercial foodservice accounted for a share of 25.0% in 2025 and is expected to see growth by 27.0% by 2035 owing to higher demand from food-service providers including hotels, restaurants, catering firms, and fast-food restaurants to cater to the ever-growing customer demand for quick and quality meals.
Frozen Food Market Dynamics
Driver
Rising Demand of Convenient And Time Saving Food Solutions
Due to increased urbanization, rising number of two income families, hectic lifestyles, and busier work schedules; there is increasing demand for convenient foods around the globe. The availability of frozen food with a longer shelf-life and quick preparation times coupled with less food wastage and product availability throughout the year while also preserving nutritive values with high-end freezing technologies are gaining increased popularity among the consumers globally. Moreover, growing penetration of modern retail formats and on-line grocers has enabled access of frozen food products to consumers globally in both developed and emerging markets.
Restraint
Demand For Fresh and Lightly Processed Food
Even with the advent of food preservation technologies like freezing, consumer preference is still skewed towards fresh food, considered both safer and of higher quality in both taste and texture. Consumer preference for fresh food has constrained sales of frozen products in various emerging economies. The operational expense in manufacturing, storage, and transport of products under refrigerated conditions, and managing the entire cold supply chain has an impact on broader market growth as any break in the supply chain can impact quality perception.
Opportunity
Growth of E-Commerce and Cold Chain Infrastructure in Emerging Markets
New avenues are being opened up by the rapid scaling of online grocery businesses, quick-commerce models and significant investments into cold chain logistics throughout the Asia Pacific region, Latin America, and into pockets of the Middle East. Enhanced refrigerated transport and ware automation systems along with improvements in last-mile cold delivery, ensure products are reaching further afield in better quality, paving the way for the growing adoption of frozen foods in developing nations, particularly with young urban consumers seeking convenience meals.
Frozen Food Market Regional Insights
What Made Europe Dominate the Frozen Food Market in 2025?
Europe, the leading market in 2025, captured a 38.0% share and is expected to maintain its supremacy, contributing a 35.0% share by 2035. During 2026-2035, Europe is projected to grow at a healthy CAGR of 5.0%, driven by high per capita frozen food consumption, wide availability of convenience meals and an adequate cold chain logistics network. Mature retail channels in nations like the United Kingdom, Germany, France and Italy consist of supermarkets that feature a wide range of frozen food assortments.
Surging demand for frozen ready meals, premium frozen fruits & vegetables, baked goods and healthier frozen alternatives in the region has also strengthened market growth.
Additionally, increasing dual-income families, demanding lifestyles of individuals, innovations in freezing technology to retain the taste and nutritional value of the food and manufacturers’ efforts to launch sustainable frozen foods with innovative packaging are boosting Europe’s market lead.
How is Asia Pacific Growing in the Frozen Food Market?
Asia Pacific is poised to become the largest and fastest growing region with 23.0% market share in 2025. Asia Pacific is predicted to experience the highest CAGR of 8.7% between 2026 and 2035 and expected to capture a massive 29.0% share by the end of the forecast period. Growing urbanization, expanding disposable incomes, transforming dietary habits and an increasing number of modern retail channels are key factors boosting frozen food consumption in China, India, Japan, South Korea and Southeast Asia.
Growth in the e-commerce grocery segment, increasing investments in the cold storage infrastructure, and an expanding network of organized retail stores have boosted the accessibility of frozen foods in urban and semi-urban areas. Rising food safety concerns and initiatives to reduce food waste and consumer preference for various international cuisines are expected to further propel regional growth.
Top 5 Countries in the Frozen Food Market
| Country | Estimated 2025 Market Position | Growth Outlook (2026–2035) |
|---|---|---|
| United States | Largest global country market | Stable growth supported by product innovation and convenience food demand |
| Germany | Largest European market | Strong growth driven by premium frozen meals and retail expansion |
| United Kingdom | Major mature market | Consistent demand for ready meals and frozen bakery products |
| China | Fastest-growing major country | High growth supported by urbanization, e-commerce, and cold chain investments |
| Japan | Leading Asian market | Growth driven by convenience foods and aging population demand |
Frozen Food Market Segmental Analysis
Product Type Insights
Ready meals segment held the most significant share in the market in 2025, with 29.0%, and are estimated to increase by 31.0% in 2035. This segment is fueled by consumer preferences toward convenient, quick, time-efficient, and easy-to-prepare meal solutions.
Increased urbanization, demanding work lifestyles, more one-person households, and availability of frozen food assortments from diverse culinary regions is propelling the growth. The innovations in ready meals, focus on healthy ingredients, and availability of gourmet options are gaining momentum globally.
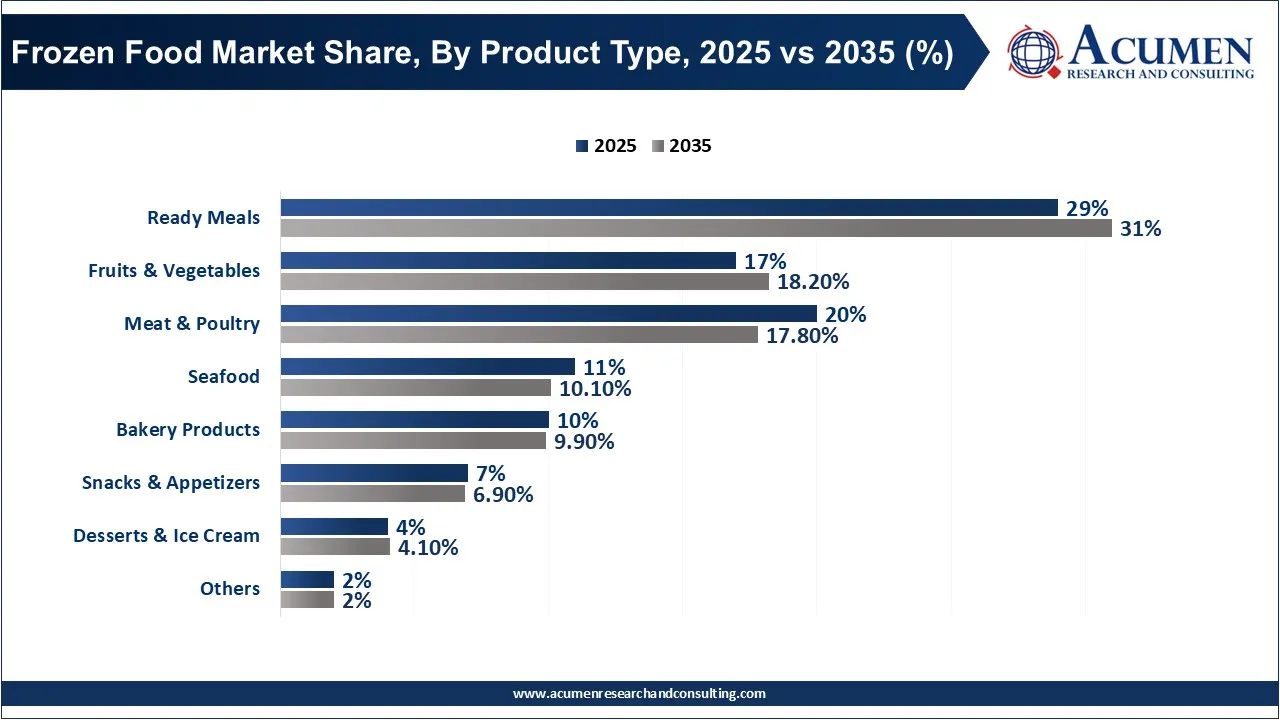
The meat & poultry segment represented the second largest segment within the market, with 20.0% of the total share in 2025. Significant protein consumption, high demand for ready-to-eat and frozen processed meat products and longer shelf-life have resulted in a sustained growth. The use of advanced freezing technologies and widespread quick-service restaurants (QSRs) are driving growth in this segment.
Food Category Insights
The non-vegetarian segment held the largest market share in 2025 with 68.0% and is anticipated to continue its dominance by capturing 64.0% of the market by 2035, expanding at a 5.2% CAGR over the 2026-2035 timeframe. Increasing global consumption of frozen chicken, seafood, meat products, and protein-based ready-to-cook meals fuels the segment growth. Significant demand from North America and Europe can be attributed to the growth of the foodservice sector and increased consumption of processed protein goods.
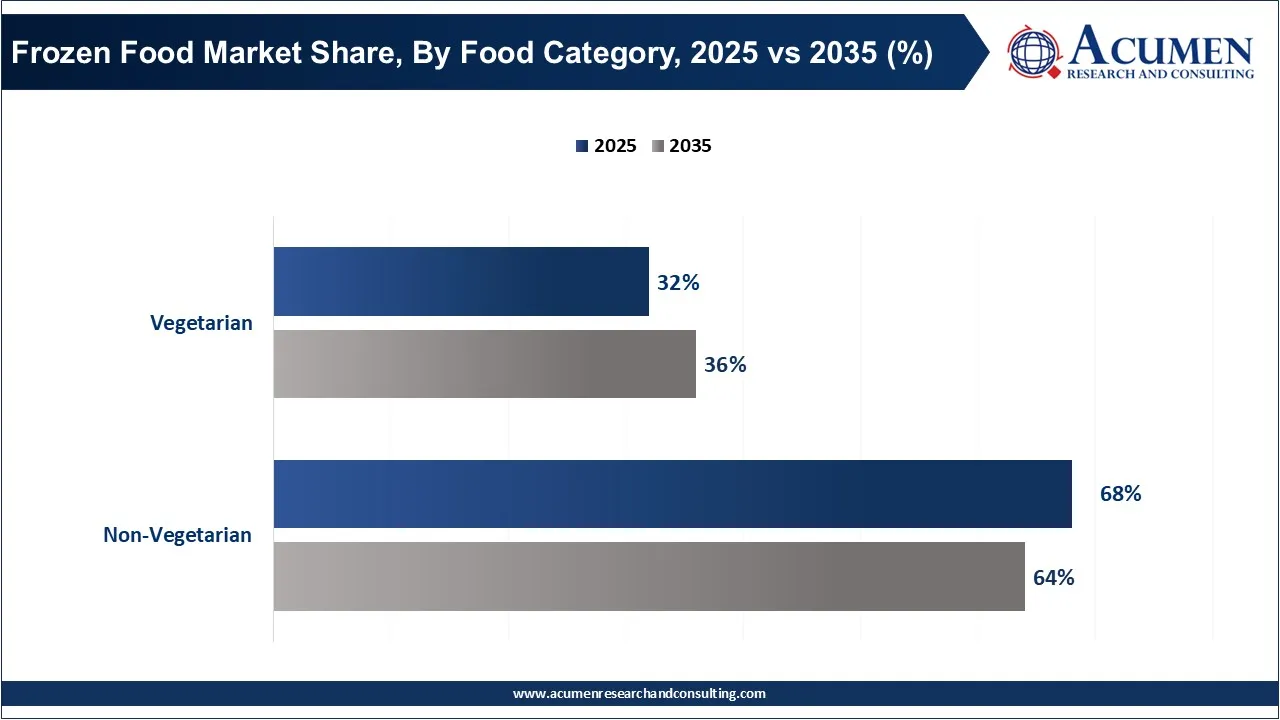
The vegetarian segment held a 32.0% market share in 2025 and is expected to register a 7.4% CAGR during the forecast period, increasing its market share to 36.0% by 2035. The segment growth is driven by the rise in flexitarian population and plant-based food trends, growing health consciousness among consumers, rise in the vegan population, and the ongoing innovation in frozen plant-based meals. Makers are offering organic frozen vegetables, protein-packed vegetarian alternatives, and plant-based ready meals.
Packaging Type Insights
In 2025 bags & pouches commanded the highest market share with 42.0% and this share is propelled by low material costs, light weight design, simple to stack, easily resealable and easy to transport applications, including effective keeping freshness of products. Flexible packaging offers cost efficiency for packaging products like fresh produce, seafood, meat and ready meals by optimizing raw material efficiency, logistics and providing cost-effectiveness, leading to increasing in overall demand for this packaging format.
Frozen Food Market Share, By Packaging Type, 2025 (%)
| Packaging Type | Revenue Share, 2025 (%) |
|---|---|
| Bags & Pouches | 42% |
| Boxes & Cartons | 28% |
| Trays | 16% |
| Tubs & Cups | 8% |
| Others | 6% |
In 2025 boxes and cartons held a share of 28.0% in the market and it is widely adopted for applications such as ready-to-eat frozen meals, ready-to-cook meals, pizzas, bakeries, ready-to-heat frozen meals, and ready-to-serve frozen meals due to optimal product protection, better labeling or marketing space and space optimization for displaying. Increasing usage of recyclable paperboard material is expected to propel segment growth in upcoming years.
Distribution Channel Insights
The supermarkets and hypermarkets generated the largest market share with 52.0% in 2025, driven by their large freezer space, wider selection of products, affordable prices and marketing promotions that attract more frozen food consumers. These large retail groups also offer both international brands of frozen food products and the private labels from one retailer to shoppers. In addition to these facilities, consumers will be able to choose their products without having to search for and visit multiple retailers.
Frozen Food Market Share, By Distribution Channel, 2025 (%)
| Distribution Channel | Revenue Share, 2025 (%) |
|---|---|
| Supermarkets & Hypermarkets | 52% |
| Convenience Stores | 15% |
| Specialty Stores | 9% |
| Online Retail | 10% |
| Foodservice | 14% |
Convenience stores segment generated 15.0% market share in 2025. The convenience store segment is driven by growing urbanization and demand for convenient shopping, including late operating hours. They also offer consumers easier access for their immediate shopping, impulse purchase and weekend purchases for their children and families. Convenience stores are well located close to residential apartments and communities.
End User Insights
In 2025, the household segment held the highest market share, accounting for 67% of the global market. The convenience of food preparation, widespread availability of freezers in homes, fast-paced lifestyles, growing awareness of frozen food being a viable and healthy alternative to fresh ingredients and growing practice of meal planning and bulk shopping habits are all contributing factors in increasing demand in the household sector.
Frozen Food Market Share, By End User, 2025 (%)
| End User | Revenue Share, 2025 (%) |
|---|---|
| Household | 67% |
| Commercial Foodservice | 25% |
| Institutional | 8% |
In 2025, the commercial foodservice segment contributed 25% of the global market share. The continued rise of restaurants, cafes, hotels, catering services, quick-service restaurants, etc across the world are adopting frozen food items for quality consistency, reduced food wastage, faster preparation time, improved operational efficiency and better supply chain management.
Frozen Food Market Key Players
- Nestle SA
- Unilever NV
- General Mills Inc.
- Conagra Brands Inc.
- McCain Foods Limited
- Kellogg Company
- Nomad Foods Limited
- Dr. Oetker GmbH
- Tyson Foods Inc.
- Birds Eye Ltd.
- Ajinomoto Co. Inc.
- Schwan's Company
Segments Covered
By Product Type
- Ready Meals
- Fruits & Vegetables
- Meat & Poultry
- Seafood
- Bakery Products
- Snacks & Appetizers
- Desserts & Ice Cream
- Others
By Food Category
- Vegetarian
- Non-Vegetarian
By Packaging Type
- Bags & Pouches
- Boxes & Cartons
- Trays
- Tubs & Cups
- Others
By Distribution Channel
- Supermarkets & Hypermarkets
- Convenience Stores
- Specialty Stores
- Online Retail
- Foodservice
By End User
- Household
- Commercial Foodservice
- Institutional
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East & Africa
Looking for discounts, bulk pricing, or custom solutions? Contact us today at sales@acumenresearchandconsulting.com
Frequently Asked Questions
Related Market Research Reports
April 2025
April 2026
April 2026
June 2024
May 2023
August 2022
February 2022
July 2021