
Medical Device Contract Manufacturing Market Size to Reach USD 247.29 Billion by 2035, Reflecting a CAGR of 12.4%
Published : 02 Sep 2026
Author : Lucas Hoffmann
What is the Medical Device Contract Manufacturing Market Size?
The medical device contract manufacturing market size was accounted for USD 85 billion in 2025 and estimated to reach at USD 247.29 billion by 2035; growing at a CAGR of 12.4% during the forecast period of 2026-2035.
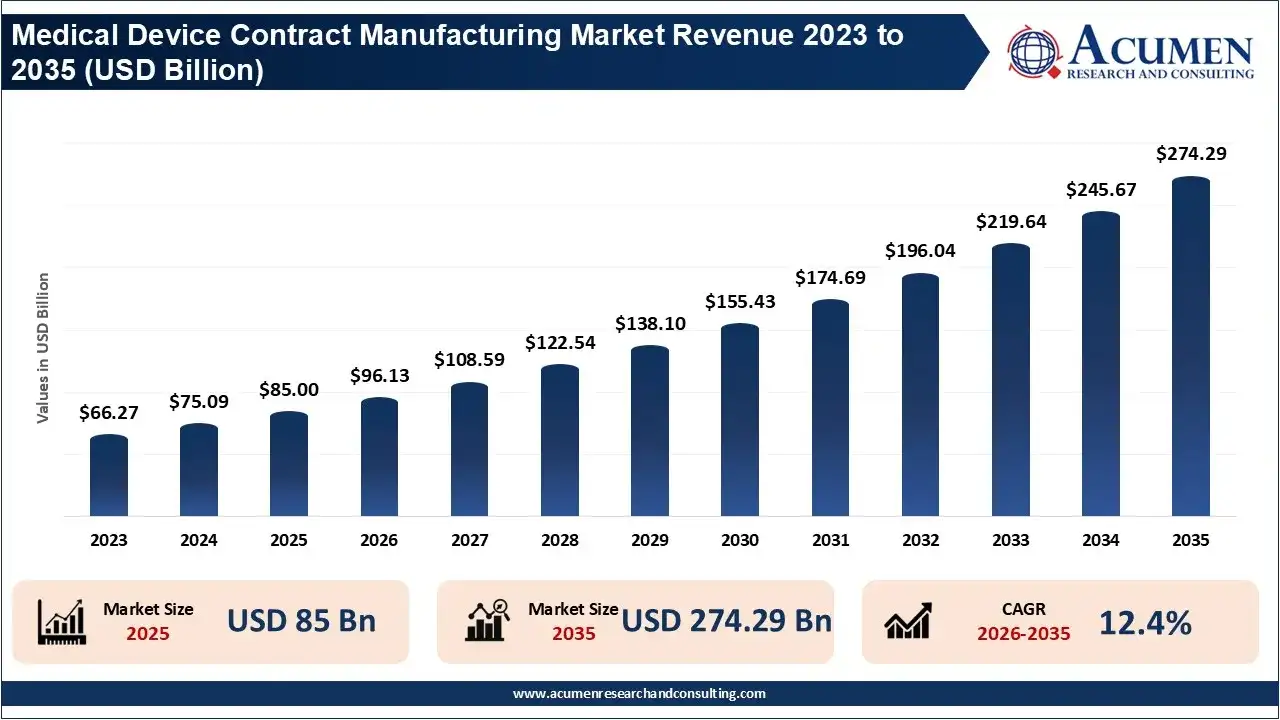
The medical device contract manufacturing market includes third party companies that contract out the manufacture of devices, that are involved in their design, development, component manufacture, assembly of the product, sterile manufacture, packaging, testing, validation and volume manufacture for device producers (OEMs). The market encompasses the manufacture of diagnostic, therapeutic and other medical equipment, such as surgical, disposable medical supplies and electrical medical equipment.
Medical devices and appliances require contract manufacturing so as that the manufacturer (OEM) can decrease product development costs, shorten the time it takes for a new product to be available in the market, reduce risk by lowering manufacturing costs, manage capacity with a need to ramp up in accordance with demand, manage inventory, and comply with applicable medical device quality regulations.
Medical Device Contract Manufacturing Market Statistics
- By product, the diagnostic segment accounted for a majority of the medical device contract manufacturing market in 2025, with a 26% market share. Growing demand for early disease detection, increasing adoption of point-of-care diagnostics, and growing OEM outsourcing of production to improve efficiencies and compliance.
- By product, the therapeutic devices segment registered a market share of 22% in 2025. Increasing prevalence of chronic diseases, higher demand for advanced therapeutic devices and a focus by device manufacturers on reducing manufacturing costs via contract manufacturing were major growth drivers.
- By service, the component manufacturing segment held a dominant 34% share in 2025. A rise in demand for highly precise components, increased device complexity, and OEM outsourcing of manufacturing to improve quality and scalability supported this segment's growth.
- By service, the device assembly and sub-assembly segment represented a significant portion of the market in 2025, with a 28% share. Medical device manufacturers are outsourcing assembly and sub-assembly operations to increase flexibility, accelerate product development, and reduce manufacturing costs.
- By device type, the non-electronic MDCM segment commanded a 51% share in 2025. Large-scale demand for surgical instruments, disposable medical devices, and diagnostics consumables, along with extensive outsourcing of traditional medical devices, supported the growth of this segment.
- By device type, the electronic MDCM segment captured 49% of the medical device contract manufacturing market share in 2025. Adoption of connected medical devices and growing demand for electronic health monitoring solutions increased the demand for specialized electronic manufacturing capabilities.
- By application, the cardiology segment was the largest application segment in 2025, with a 22% market share. This can be attributed to an increasing prevalence of cardiovascular diseases, high demand for minimally invasive treatment procedures and ongoing development in implantable cardiac devices.
- By application, the diagnostic imaging segment was the second largest segment and accounted for a 16% market share in 2025. Growing adoption of advanced diagnostic imaging systems and increasing demand for precision diagnostics are the key factors propelling the growth of this segment.
How Will Rising Demand for High-Complexity Medical Devices Create New Growth Opportunities?
The increasing use of minimally invasive surgical equipment, implantable medical devices, robotic assisted medical technology, and wearable medical technology & interconnected diagnostic equipment are driving massive opportunities for contract manufacturers. These devices require complex and precise engineering capabilities, custom materials, innovative assembly processes, and complex regulations. Many medical OEM’s are outsourcing development and production of these devices because they do not possess this internal expertise.
Also, there is significant demand for these types of high-value devices driven by the world’s aging population, chronic diseases, the desire for customized, digital health and remote monitoring capabilities. Contract manufacturers that invest in robotics and automated manufacturing, dedicated cleanroom environments, electronic device integration capabilities, and end-to-end contract manufacturing services will be poised to succeed as the global medical device manufacturing grows.
Latest Trends in the Medical Device Contract Manufacturing Market
- Rising adoption of end-to-end manufacturing services: Medical device OEMs are increasingly outsourcing the complete product lifecycle from design and prototyping to assembly, packaging, and logistics to reduce costs and shorten time-to-market.
- Expansion of manufacturing capacity in Asia-Pacific: Global contract manufacturers are expanding facilities in countries such as China, India, Malaysia, and Singapore to leverage lower production costs, skilled labor, and growing regional demand.
- Growing integration of automation and Industry 4.0 technologies: Manufacturers are adopting robotics, artificial intelligence, digital twins, and smart factory solutions to improve production efficiency, product quality, and traceability.
- Increasing demand for electronic and connected medical devices: The rapid adoption of wearable health devices, remote patient monitoring systems, and IoT-enabled medical equipment is driving investments in advanced electronics manufacturing capabilities.
Medical Device Contract Manufacturing Market Regional Outlook
North America occupied the largest share in the global medical device contract manufacturing market with 36.0% in 2025 and is growing at CAGR of 10.1% from 2026 to 2035. North America holds major share owing to a high presence of medical device OEMs, robust healthcare infrastructure, and a mature regulatory landscape promoting the standards of quality manufacturing.
Continuous trend of outsourcing activities for the purpose of cutting down on production costs, expediting product launch and to meet strict regulatory norms by medical device firms has been fuelling the regional market growth. Increased adoption of minimally invasive devices, digital health devices, surgical robot systems, implantable devices has driven steady growth for the market players in the North America market.
The market in the Asia-Pacific region accounted for 30.0% of the overall market share in 2025, and estimated to account for 40.0% of the global market share in revenue terms by 2035 with the highest CAGR of 16.0% over the forecast period. As of now the region has been turning out to be the one stop shop to outsource the production for medical devices with the factors of cost competitiveness, huge base of engineering workforce and strong electronics manufacturing.
Many nations such as China, India, Singapore, and Malaysia are witnessing increased focus and investment on CDMOs, automation in production process and cutting edge infrastructure of production, increasing demand for medical devices in the region will also have a major impact on the overall growth of the market, coupled with well established and supportive government policies on manufacturing sector, rise in export, expanding healthcare budgets and global demand for better healthcare devices and instruments by global players (OEMs).
Top Companies in the Medical Device Contract Manufacturing Market
Key market participants that manufacture such complex medical components and products include Jabil Inc., Flex Ltd., Sanmina Corporation, TE Connectivity Ltd., Integer Holdings Corporation, Viant Medical, Phillips-Medisize (a Molex company), Celestica Inc., Nortech Systems Incorporated, Gerresheimer AG, West Pharmaceutical Services, Inc. and Kimball Electronics, Inc.
The key market players have the capabilities for a full range of contract manufacturing services, from the design and development phase to the manufacture of critical components, device assembly, sterilisation, packaging, testing, verification, and the supply chain and distribution of final products.
The manufacturers have a large manufacturing presence globally with broad capabilities in areas such as the manufacturing processes required to ensure strict regulatory compliance and continue to invest in innovative, state-of-the-art manufacturing equipment, technologies and processes. These players enable global medical device companies in both small and large scales to speed their time to market while minimising costs and enabling scale.
Segments Covered in the Report
By Service Type
- Component Manufacturing
- Device Assembly & Sub-Assembly
- Sterilization & Packaging Services
- Design & Development Services (D&D)
- Testing & Validation Services
By Product Type
- Diagnostic Devices
- Therapeutic Devices
- Surgical Devices
- Implants
- Consumables & Disposables
By Device Type
- Electronic MDCM
- Non-Electronic MDCM
By Application
- Cardiology
- Diagnostic Imaging
- Orthopedic
- Endoscopy
- Dental
- Diabetes Care
- In-Vitro Diagnostics
- Respiratory
- Others
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East & Africa
Contact Us:
Mr. Richard Johnson
Acumen Research and Consulting
India: +91 8983225533