
Medical Device Contract Manufacturing Market Size, Share, Report 2026 to 2035
Medical Device Contract Manufacturing Market (By Service Type: Component Manufacturing, Device Assembly & Sub-Assembly, Sterilization & Packaging Services, Design & Development Services (D&D), Testing & Validation Services; By Product Type: Diagnostic Devices, Therapeutic Devices, Surgical Devices, Implants, Consumables & Disposables; By Device Type: Electronic MDCM, Non-Electronic MDCM; By Application: Cardiology, Diagnostic Imaging, Orthopedic, Endoscopy, Dental, Diabetes Care, In-Vitro Diagnostics, Respiratory, Others) - Global Industry Analysis, Size, Share, Growth, Trends, Regional Analysis And Forecast 2026 To 2035
- Last Updated: 19 Jun 2026
- Report Code: ARC1851
- Category: Healthcare and Pharmaceuticals
Medical Device Contract Manufacturing Market Size, Forecast 2026 to 2035
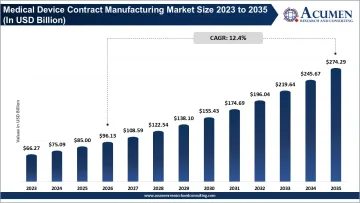
The global medical device contract manufacturing market size was valued at USD 85 billion in 2025 and is estimated to exceed around USD 274.29 billion by 2035, growing at a CAGR of 12.4% during the forecast period from 2026 to 2035.
Report Highlights
- By product, diagnostic segment dominated the medical device contract manufacturing market with a 26% share in 2025, owing to increasing demand for disease diagnosis, expansion of point-of-care testing, rising chronic disease burden, and growing outsourcing of diagnostic device production.
- By product, the therapeutic devices held the second-largest share of 22% in 2025, driven by growing adoption of treatment and patient management devices, increasing prevalence of chronic diseases, and rising demand for cost-efficient manufacturing solutions.
- By service, the component manufacturing segment dominated the market at 34% market share in 2025, owing to rising outsourcing of precision-engineered components, growing demand for cost-efficient production and rising complexity of medical devices requiring specialized manufacturing expertise.
- By service, device assembly and sub-assembly held the second-largest share of 28% in 2025, driven by growing demand for outsourced assembly services and manufacturers’ focus on improving operational efficiency.
- By device type, the non-electronic MDCM segment led the market with 51% share in 2025 owing to extensive outsourcing of consumables and surgical instruments.
- By device type, the electronics MDCM segment accounted for 49%share in 2025 driven by increasing demand for connected medical devices and advanced electronic medical products
- By application, cardiology constitutes one of the largest application segments held 22% share in 2025 driven by a growing global burden of cardiovascular diseases coupled with increasing demand for minimally invasive cardiac devices and implantable medical devices.
- By application, diagnostic imaging is identified as one of the large application areas, held 16% of market share in 2025; owing to rising use of advanced imaging devices for early disease diagnosis, cancer identification and precision healthcare solutions globally.
Government & Private Investments
| Country | Government Initiatives | Private Investments & Industry Developments |
|---|---|---|
| United States | FDA support programs for medical technology innovation and healthcare manufacturing modernization are encouraging advanced medical device production and domestic supply chain strengthening. | Major investments by medical technology companies in AI-enabled devices, robotic surgery systems, and advanced manufacturing facilities continue driving outsourcing demand. |
| China | “Made in China 2025” and healthcare modernization initiatives support domestic medical device manufacturing, hospital expansion, and healthcare technology innovation. | Chinese and multinational companies are heavily investing in medical device production facilities, diagnostics manufacturing, and smart healthcare technologies. |
| India | Production Linked Incentive (PLI) Scheme for medical devices and establishment of medical device parks are supporting domestic manufacturing growth. | Increasing investments by private healthcare companies and global OEMs in contract manufacturing facilities and affordable healthcare technologies are strengthening market expansion. |
| Japan | Government programs supporting digital healthcare, robotics, and precision medicine are accelerating advanced medical device development. | Japanese manufacturers continue investing in robotic-assisted surgery systems, diagnostic imaging technologies, and miniaturized medical device manufacturing. |
| South Korea | Government-backed smart healthcare and biotech initiatives are encouraging innovation in wearable healthcare technologies and medical electronics manufacturing. | Rising investments in AI-integrated diagnostics, telemedicine systems, and semiconductor-based medical devices are expanding contract manufacturing opportunities. |
Market Dynamics
Driver
Increasing Outsourcing of Medical Device Manufacturing Operations
The increasing trend of outsourcing manufacturing operations by the medical device companies is a significant factor driving the medical device contract manufacturing market. The Original Equipment Manufacturers (OEMs) are partnering with Contract Manufacturing Organizations (CMOs) to reduce the manufacturing costs, optimize the operation efficiency, faster product commercialization, and to focus on the core strengths such as research, innovation, and marketing. The increasing complexity of medical devices such as wearable healthcare devices, robotic-assisted surgical systems, implantable devices, AI-powered diagnostic systems are massively increasing the need for specialized manufacturing expertise.
Restraint
Strict Regulatory Compliance and Quality Standards
The increasing stringent regulatory requirements and complex quality compliance standards are considered to be major restraining factor for the medical device contract manufacturing market. The contract manufacturers need to adhere to the strict guidelines imposed by health regulatory agencies like FDA, European regulatory agencies, and other international healthcare organizations. The manufacturing process for the medical devices has a stringent quality control, validation procedure, sterilisation method, document process and product testing requirements for patient safety andregulatory approval.Failure to comply with regulatory guidelines and quality standards may lead to product recall and a significant increase in operational cost, negatively impacting market growth.
Opportunity
Rising Demand for Wearable, Implantable, and Smart Medical Devices
Growing demand for the wearable healthcare devices, smart implantable devices and connected medical devices has created significant opportunities in medical device contract manufacturing market. Increasing use of remote patient monitoring, telemedicine, AI-powered diagnostics and personalized medicine solutions has increased the demand of electronic medical devices at a large scale. CMOs are actively investing in automation, precision engineering, miniaturization technologies and digital manufacturing technologies for the production of advanced healthcare devices.
Segmental Analysis
Service Insights
The component manufacturing segment led the medical devices contract manufacturing market in 2025 and represents about 34% of the overall market share. This segment is primarily driven by increased demand for outsourced manufacturing of high-precision medical device components such as molded plastic components, metal components, electronic components, electronic assemblies and other specialized assemblies.
Medical devices companies have entered into contracts with contract manufacturers to minimize their manufacturing costs and improve the production process and to gain access to advanced manufacturing technologies at lower initial capital expenditures. Moreover, increasing sophistication of medical devices, coupled with regulatory standards, has compelled OEMs to approach capable contract manufacturing companies for the production of high-quality medical devices components. Growing manufacturing of diagnostic devices, surgical devices and implantable medical devices further bolster the segment's growth.
Medical Device Contract Manufacturing Market Share, By Services, 2025 (%)
| Service Type | Revenue share, 2025 (%) |
|---|---|
| Component Manufacturing | 34% |
| Device Assembly & Sub-Assembly | 28% |
| Sterilization & Packaging Services | 16% |
| Design & Development Services (D&D) | 12% |
| Testing & Validation Services | 10% |
The devices assembly and sub-device assembly segment had the second-largest market share of 28% in 2025. This is driven by increased outsourcing of the final medical devices assembly to external manufacturing service providers. Companies are opting to focus on core business of research, innovation, and commercialization and on the other hand entrusting the assembly of their devices to contract manufacturers.
Product Insights
In 2025, the diagnostic devices segment was the largest share of the medical device contract manufacturing market, and held a share of approximately 26% of the global market. Early disease detection, growing usage of point-of-care testing solutions, increasing demand for medical imaging and laboratory diagnostic devices across the globe, are the key factors attributed to the leading share of the diagnostic devices segment. With several medical device companies increasingly outsourcing production of diagnostic devices, to avail advanced manufacturing techniques and technologies, cost effectiveness, and manufacturing compliance. Rise in prevalence of chronic diseases, increasing focus on preventive healthcare, and advancements in diagnostic devices are contributing to the continued growth in this segment.
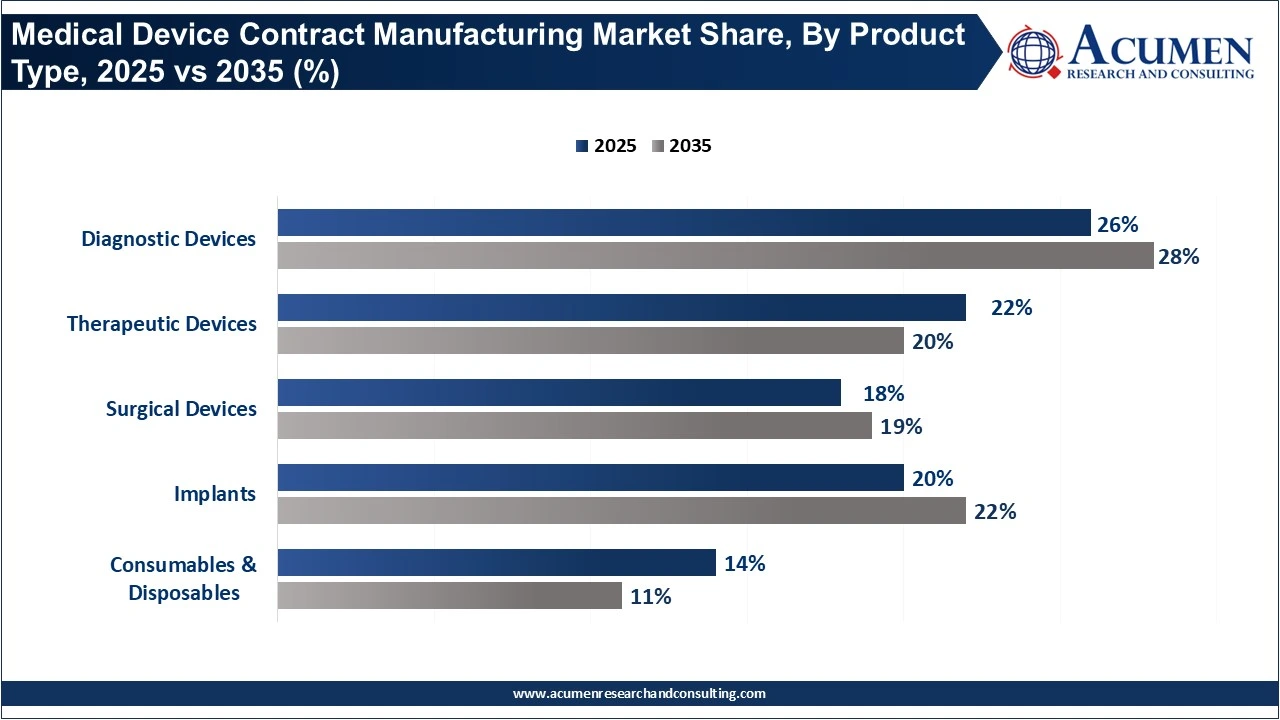
In 2025, the therapeutic devices segment held the second largest share of the global medical device contract manufacturing market, holding a share of 22% in 2025. Increasing demand for devices used in therapy and treatment, rehabilitation and maintenance, is the driving factor attributed to the significant share held by this segment. Increased prevalence of chronic diseases including, cardiovascular diseases, diabetes, respiratory disorders and neurological disorders is accelerating the demand for therapeutic medical devices globally. Contract manufacturing organizations are seeing a rapid increase in the demand for technologically advanced therapeutic devices to reduce overall operational costs and improve the production efficiency.
Device Type Insights
The non-electronic MDCM segment dominated the medical device contract manufacturing market in 2025 with an approximate market share of 51%. The increasing trend of outsourcing the manufacturing of consumables, surgical instruments, orthopaedic implants, catheters, drug delivery devices and other mechanically operated medical devices has attributed to the significant share of this segment in the market. The medical device manufacturers are increasing outsourcing to the contract manufacturers to reduce costs, to have scalable production and adhere to strict regulations along with being able to concentrate on core areas such as research and product development. Additionally, increasing requirement for less-invasive surgical devices and disposable medical devices is also contributing to the growth of non-electronic MDCM globally.
Medical Device Contract Manufacturing Market Share, By Device, 2025 (%)
| By Device Type | Revenue share, 2025 (%) |
|---|---|
| Electronic MDCM | 49% |
| Non-Electronic MDCM | 51% |
The electronic MDCM segment contributed to 49% of the total market share in 2025, as a result of increasing adoption of advanced technologically innovative medical devices embedded with sensors, microelectronics, connectivity and digital monitoring. The increasing demand for diagnostic imaging systems, patient monitoring devices, wearable medical technology, implantable electronic devices and remote healthcare devices has resulted in increased outsourcing demands for highly specialized electronic manufacturing capabilities. The incorporation of Artificial Intelligence, IoMT, smart healthcare technology within medical devices are driving more medical device manufacturers to join hands with MDCMs capable of electronic design and manufacturing at high end.
Application Insights
The cardiology segment represented one of the most significant application areas, holding 22% in 2025 driven by the increased global prevalence of cardiovascular diseases and rising demand for advanced treatment of such diseases. CMOs are extensively involved in manufacturing cardiac pacemakers, cardiac monitors, stents, catheters, ICD devices and minimally invasive cardiac devices.
Medical Device Contract Manufacturing Market Share, By Application, 2025 (%)
| By Application Type | Revenue share, 2025 (%) |
|---|---|
| Cardiology | 22% |
| Diagnostic Imaging | 16% |
| Orthopedic | 14% |
| Endoscopy | 10% |
| Dental | 7% |
| Diabetes Care | 8% |
| In-Vitro Diagnostics | 12% |
| Respiratory | 7% |
| Others | 4% |
Another major segment, diagnostic imaging, held 16% market share in 2025, faces a steep demand on account of increasing requirements for diagnosis and early detection of diseases globally. CMOs in this segment provide services for manufacturing of MRI systems, CT scanners, ultrasound equipment, X-ray devices and image guided surgical instruments.
Regional Analysis
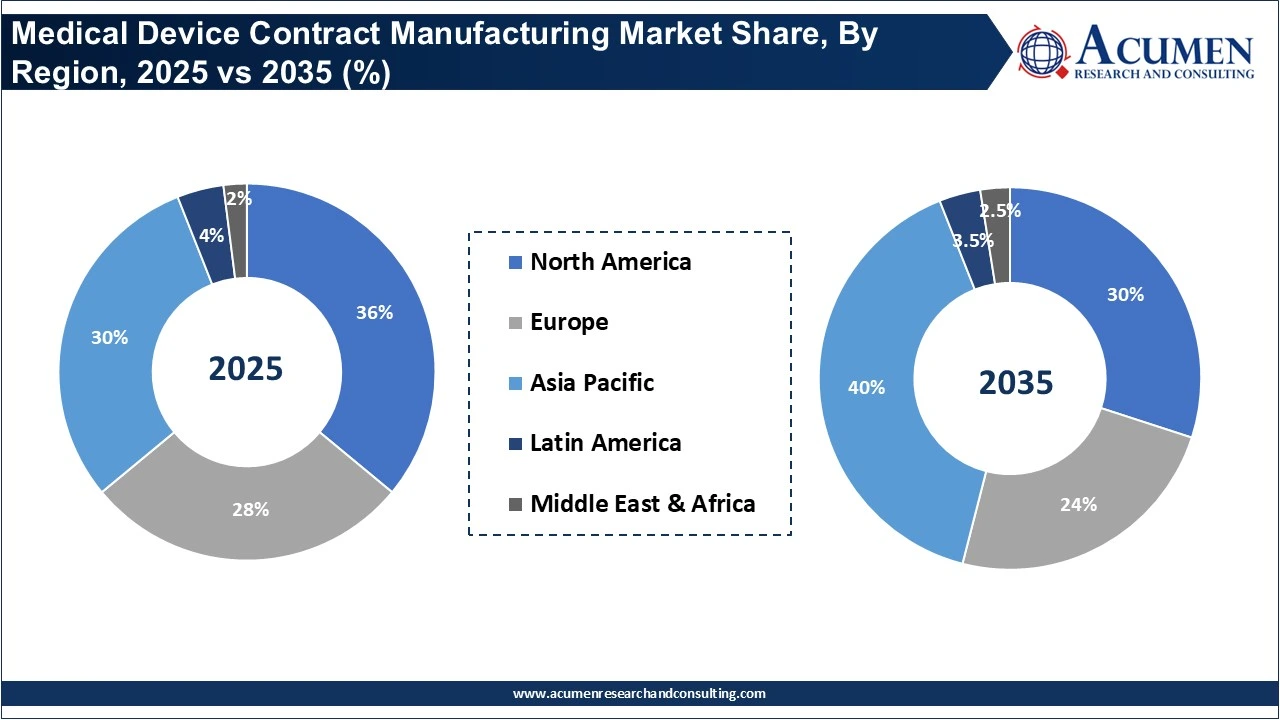
- The North America medical device contract manufacturing market size was estimated at USD 30.60 billion in 2025 and is forecasted to hit around USD 82.29 billion by 2035 with a CAGR of 10.1% from 2026 to 2035.
- The Europe medical device contract manufacturing market size was valued at USD 23.80 billion in 2025 and is predicted to surpass around USD 65.83 billion by 2035, growing at a CAGR of 10.4% from 2026 to 2035.
- The Asia-Pacific medical device contract manufacturing market was valued at USD 25.50 billion in 2025 and is anticipated to reach around USD 109.71 billion by 2035, reflecting a CAGR of 16% from 2026 to 2035.
Why does North America dominates in the medical device contract manufacturing market?
The North America region led the global medical device contract manufacturing market owing to presence of major leading medical device manufacturers, robust healthcare infrastructure, increased spending on healthcare and rise in contract manufacturing of medical devices by original equipment manufacturers (OEMs). The medical technology environment is very developed in the North America region owing to consistent innovation in diagnostic devices, implantable medical devices, robotic assisted surgery systems and minimal invasive solutions.
In North America, the United States is expected to be the leading market due to increase in demand of precisely manufactured medical devices, rise in incidence of chronic diseases and rise in implementation of digital healthcare technologies. Companies manufacturing medical devices in the North America region are increasingly signing contract manufacturing agreements with contract manufacturing organizations (CMOs) in order to minimize their operating costs, speed up product development cycles, enhance supply chain capabilities and comply with regulations.
Why is Asia-Pacific expected to witness the highest growth rate in the global medical device contract manufacturing market?
The Asia-Pacific region is expected to witness the highest growth rate in the global medical device contract manufacturing market during the forecast period due to growing healthcare investment, rise in manufacturing capabilities, low manufacturing cost and rapid rise in healthcare demand in emerging economies. China, India, Japan, South Korea and Singapore are becoming centers for medical device manufacturing and contract manufacturing.
In the Asia-Pacific region, the market benefits from the increasing chronic disease patient population, adequate workforce for manufacturing and growing number of private sector participants along with the increasing demand for advanced medical technology, and improving healthcare infrastructure.
Top Companies
- Thermo Fisher Scientific Inc.
- Integer Holdings Corporation
- FLEX LTD.
- Sanmina Corporation
- Nipro Corporation
- Celestica Inc.
- Phillips-Medisize
- Viant Technology LLC
- West Pharmaceutical Services, Inc.
- Mack Molding
- Cirtec Medical
- Cogmedix
- Plexus Corp.
- Synecco Ltd
- TE Connectivity
- Keller Technology Corp.
- HDA Technology, Inc.
Recent Developments
- March 2026 – Jabil Healthcare announced that it is expanding its medical device manufacturing capabilities in North America in order to increase manufacturing of robotic surgical systems, wearable technologies, and connected healthcare technologies.
- January 2026 - Flex Ltd. Has unveiled a new smart manufacturing technology focused on the AI of diagnostics, connected healthcare technologies and remote monitoring devices in the medical device industry.
- October 2025 – Integer Holdings Corporation entered into a broadened partnership with manufacturers of cardiovascular devices and supported the production of next generation catheters and minimally invasive cardiac implants.
Segments Covered in Report
By Service Type
- Component Manufacturing
- Device Assembly & Sub-Assembly
- Sterilization & Packaging Services
- Design & Development Services (D&D)
- Testing & Validation Services
By Product Type
- Diagnostic Devices
- Therapeutic Devices
- Surgical Devices
- Implants
- Consumables & Disposables
By Device Type
- Electronic MDCM
- Non-Electronic MDCM
By Application
- Cardiology
- Diagnostic Imaging
- Orthopedic
- Endoscopy
- Dental
- Diabetes Care
- In-Vitro Diagnostics
- Respiratory
- Others
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East & Africa
Looking for discounts, bulk pricing, or custom solutions? Contact us today at sales@acumenresearchandconsulting.com
Frequently Asked Questions
Other Healthcare and Pharmaceuticals Reports
March 2025
February 2025
June 2024
June 2026