
India Green Hydrogen Market Size to Surge USD 11,248.92 Million by 2035, Expanding a CAGR of 92.7%
Published : 03 Sep 2026
Author : Raghuram Nair
What is the India Green Hydrogen Market Size?
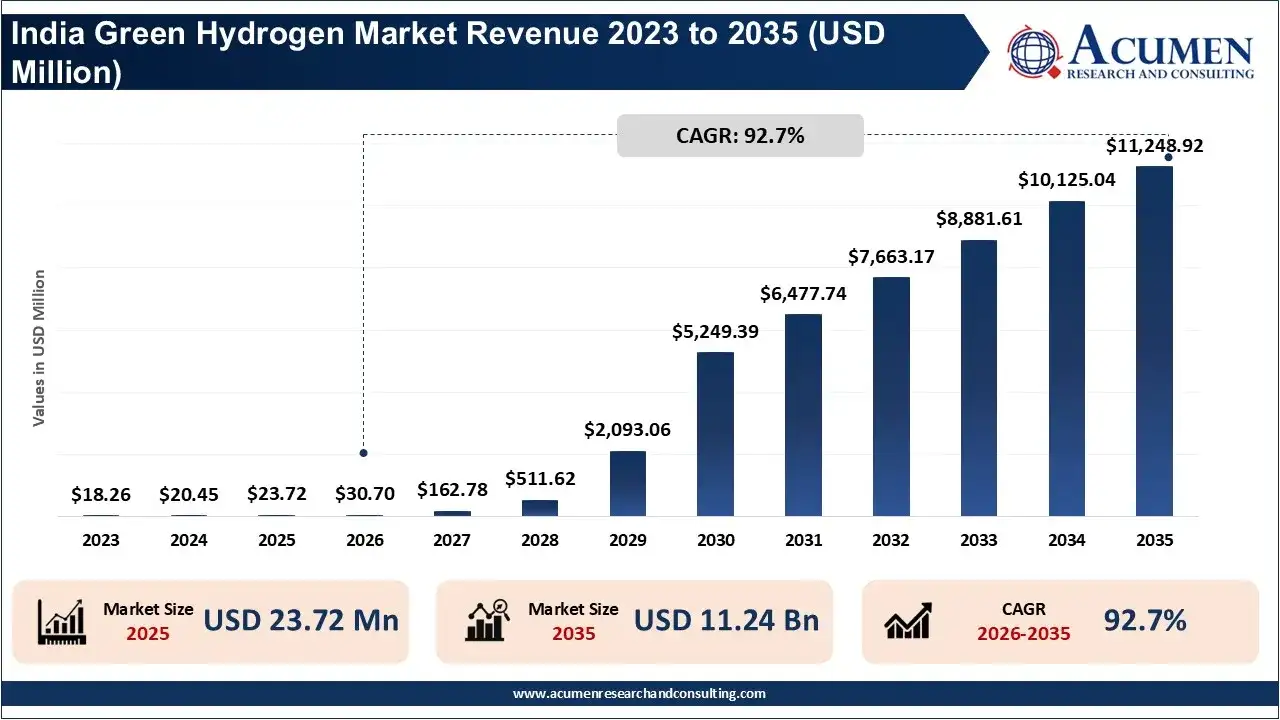
The India green hydrogen market was valued at USD 23.72 million in 2025 and is projected to surge USD 11,248.92 million by 2035, expanding at a compound annual growth rate (CAGR) of 92.7% from 2026 to 2035.
India Green Hydrogen Market Overview & Scope
Initiatives such as the National Green Hydrogen Mission, Production incentives, and renewable energy targets have created a supportive environment for large-scale hydrogen project developments. This regulatory backing encourages domestic and foreign investment in production facilities, electronics manufacturing, and related infrastructure. Additionally, India's commitment to reducing greenhouse gas emissions and achieving net-zero goals has increase the strategic importance of green hydrogen, and it is emerging as a foundational fuel for energy transition across major sectors.
Another major growth factor is the increasing demand for low-carbon alternatives in energy-intensive industries and power systems. Demand is also developing in the fertilizer sector, with prices discovered for the production and supply of 724,000 tonnes per annum of green ammonia to 13 fertilizer units across India. At the technology level, increasing domestic electrolyzer manufacturing is expected to improve supply availability and support cost reductions, with 3,000 MW per year of manufacturing capacity already awarded under the government incentive program.
India Green Hydrogen Market Statistics
- By 2025, prices had been discovered for the production and supply of 724,000 tonnes per annum of green ammonia to fertilizer units, indicating growing demand for green hydrogen-derived products in India.
- As of February 2026, 18 companies had been awarded incentives for green hydrogen production projects representing a cumulative capacity of 862,000 tonnes per annum, according to the latest government progress update.
- Under the electrolyzer manufacturing program, 15 companies had been awarded incentives for a combined manufacturing capacity of 3,000 MW per year, strengthening India's domestic electrolyzer supply chain.
- The first tranche of SIGHT-approved electrolyzer projects represents 1,500 MW of annual manufacturing capacity, while the second tranche adds another 1,500 MW, taking the approved capacity across these two tranches to 3,000 MW per year.
- The latest approved SIGHT production projects include individual annual green hydrogen capacities of up to 90,000 tonnes, with ACME Cleantech, Greenko, Reliance, Welspun, and other major companies participating in the program.
- The government has set an associated renewable energy requirement of about 125 GW to support the 5 MMT per annum green hydrogen production target by 2030, linking hydrogen expansion directly with India's renewable power build-out.
- India’s green hydrogen project pipeline is expanding beyond production, with projects covering green ammonia, mobility, refining, shipping, and industrial applications; the MNRE project database includes projects ranging from individual electrolyzer capacities of hundreds of MW to more than 1 GW.
Governments' policies and Strategic Initiatives: Market’s Notable Move
Strong government support is a major driver of the India green hydrogen market. Initiatives such as the National Hydrogen Mission, renewable energy incentives and favorable policy frameworks are encouraging investment in predictive facilities, electrolyzer technology development, and associated infrastructure. This regulatory backing reduces financial and operational risks for companies, accelerates project development, and aligns with India's decarbonization goals, creating a structured environment for market growth.
High Production Cost and Infrastructure Limitations: Market’s Challenge
A significant restraint for the India green hydrogen market is the cost of green hydrogen production and limited infrastructure. The technology of electrolyzers, renewable energy integrations, and systems of hydrogen storage needs significant capital investment, which makes green hydrogen less cost-competitive compared to conventional fossil-based fuels. Additionally, the absence of hydrogen pipelines, storage systems, and standardized regulations created logistical challenges that can delay commercialization and constrain large-scale adoption, even as production capacity expands.
India Green Hydrogen Market Supply Chain Analysis
- Renewable Energy Supply – The most important upstream inputs into green hydrogen production are Solar power and wind power because the electrolyzers need electricity generated by renewables to electrolyze water into its constituent components: oxygen and hydrogen.
- Electrolyzer Supply – Alkaline and PEM technologies represent the dominant technologies in electrolyzer supply chain and domestic manufacturing has been bolstered by the Strategic Interventions for Green Hydrogen Transition (SIGHT) program.
- Water supply – Purified water is a critical element of electrolyzers’ raw material supply. A significant number of opportunities lie in water-treatment, water-recycling, or water-desalination technology solutions which are essential for any large green hydrogen projects especially for those situated in water scarce locations.
Technological Advancements and Export Potential in India’s Green Hydrogen Sector
| Development Area | Key Development | Impact on India’s Green Hydrogen Market |
|---|---|---|
| Electrolyzer technology | Expansion of domestic alkaline and PEM electrolyzer manufacturing | Reduces dependence on imports and supports lower-cost green hydrogen production |
| Renewable energy integration | Increasing integration of solar and wind power with electrolyzers | Improves the availability of renewable electricity for hydrogen production |
| Green hydrogen production | Incentives supporting large-scale green hydrogen production projects | Accelerates commercial-scale production and strengthens domestic supply |
| Hydrogen hubs | Development of integrated green hydrogen hubs | Creates centralized ecosystems for production, storage, distribution, and utilization |
| Storage technology | Development of advanced hydrogen storage and handling solutions | Supports reliable supply and enables transportation to distant consumption centers |
| Transportation infrastructure | Expansion of pipelines, ports, and hydrogen-derived fuel logistics | Improves domestic distribution and strengthens export readiness |
| Green ammonia | Increasing investments in green ammonia production | Creates an easier-to-transport hydrogen derivative for international trade |
| Export infrastructure | Development of port-based green hydrogen and ammonia facilities | Enables India to access international markets across Asia and Europe |
| International demand | Rising demand for low-carbon hydrogen and green ammonia globally | Creates significant long-term export opportunities for Indian producers |
Top Investors in India Green Hydrogen Market
Green hydrogen project pipeline in India, which has garnered investments from leadingenergy , industrial , infrastructure and renewable power developers including reliance Industries, Larsen & Toubro, adani Group, NTPC, ACME Group, ReNew, Greenko, Welspun New Energy, avaada and gail. Major players like reliances have begun setting up green hydrogen ecosystem spanning the integrated value chain including renewable energy, electrolyzers, green hydrogen production and downstream applications.
Larsen & Toubro is also increasing its footprint both in electrolyzers and green hydrogen deployment, with its electrolyzer arm having bagged manufacturing capacity award for 300MW/annum for 5 years under National Green Hydrogen mission.
AcME group and greenko are some of the largest entities under government backed green hydrogen production projects. They have been awarded 90000tpa allocation each under SIGHT program.
Market Segmentation
By Technology
- Alkaline Electrolyzer
- PEM Electrolyzer
- SOEC Electrolyzer
By Distribution Channel
- Pipeline
- Cargo
By Application
- Refining
- Fertilizers & Ammonia
- Steel & Iron
- Chemicals & Methanol
- Mobility & Shipping
- Transport
- Others
By Market Destination
- Domestic Consumtion
- Export
By Region (Within the country)
- North India
- West India
- South India
- East India
- Northeast India
Contact Us:
Mr. Richard Johnson
Acumen Research and Consulting
India: +91 8983225533